
Ownership and NCI · Track 2 · Tutorial 3 of 4
Take control of a company you already part-own
Available on ProPremium
When the group already owns part of a company and buys enough to control it, the old stake is revalued and the company starts being consolidated. Record the purchase once, and BrizoConsol handles both.
1Understand what changes at control
In the running example the group has owned 40% of Company E since January 2025, as an associate. In October 2026 it buys another 30% for 750,000, taking it to 70% and control.
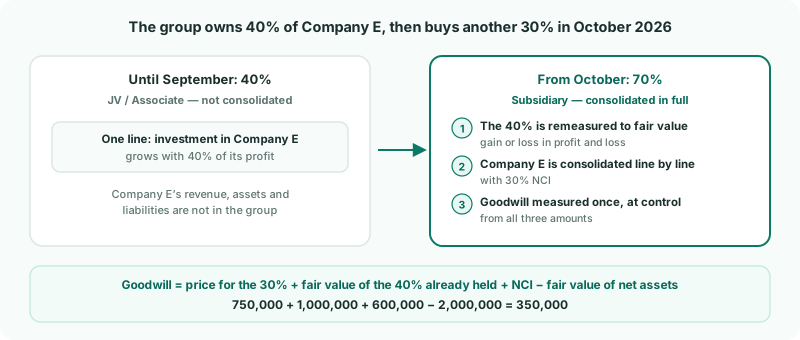
| Until September | Company E is a JV / Associate. Its figures are not consolidated; BrizoConsol posts the group’s 40% share of its profit as JV entries. |
|---|---|
| In October | The 40% is treated as if sold and bought back at fair value: the difference to its carrying amount is a gain or loss in profit and loss. |
| From October | Company E is consolidated line by line, with 30% NCI, and goodwill is measured once — from the price paid, the fair value of the 40%, and the NCI. |
This tutorial is one scenario for the example group described in Load the month and see what is missing; the other tutorials in this track are separate scenarios, not a sequence. Your own companies and amounts will differ, so the Check boxes say what to compare in your own group.
2Check the earlier stake is recorded
- Open Ownership & Equity → Ownership, and click Company E in Group structure.
- Under Share purchases and sales, check there is a Bought 40% record marked significant influence, in the month it was bought.
If it is missing, add it first: + Record, Bought shares, the month, 40, JV / Associate, and the investment cost. BrizoConsol uses this record to know the group already held a stake without control — which is what makes the next purchase a step acquisition.
To see the equity-method figures posted so far, open Ownership & Equity → JV / Associate Report for Company E. How the equity method is set up and posted is covered in Account for associates and joint ventures.
3Choose the remeasurement account
- On the Ownership page, open Posting accounts with the gear beside Group structure.
- Choose a profit and loss account for Gain/loss remeasuring the stake already held, and click Save.
The gain or loss on the old stake is posted here. The acquisition cannot be posted until this account is set.
4Record the purchase that gives control
- Beside Company E’s Share purchases and sales, click + Record, then Bought shares.
- Choose your group, Oct-2026, 30, and Subsidiary.
- Enter the Investment cost for the 30% (750,000) and the Net assets at date (fair value) of the whole company (2,000,000).
- The dialog now says the group already held 40% without control. Enter the Previously held interest fair value, 1,000,000.
- Click Add Record.
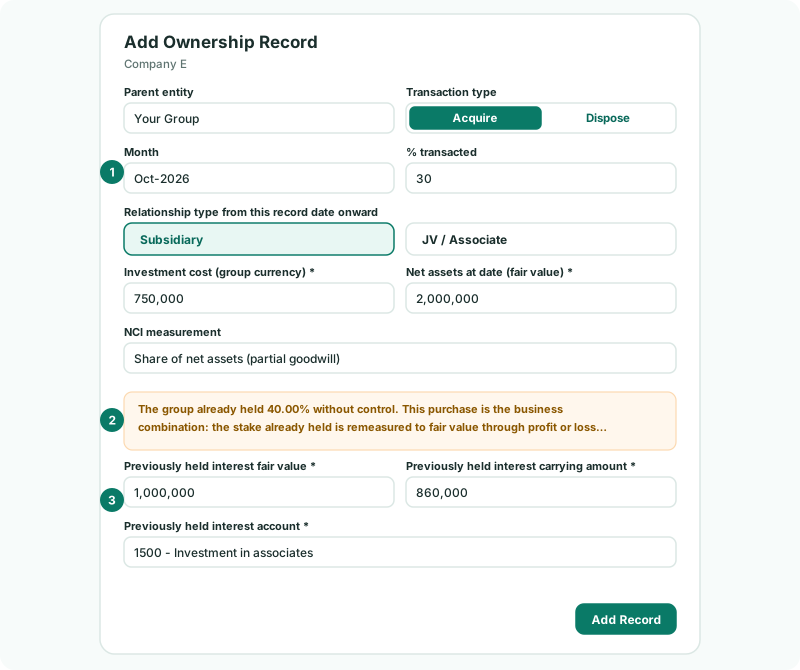
| Previously held interest fair value | What the 40% is worth at the date of control — in the example 1,000,000, from the same valuation as the purchase price. |
|---|---|
| Carrying amount | Not asked for. BrizoConsol has posted the 40% by the equity method, so it takes the carrying amount from Associate/JV - investment at the day before the purchase — here 860,000 — and clears that account at fair value. The 140,000 difference is the remeasurement gain. |
All amounts are in the group currency. BrizoConsol works out two figures from them:
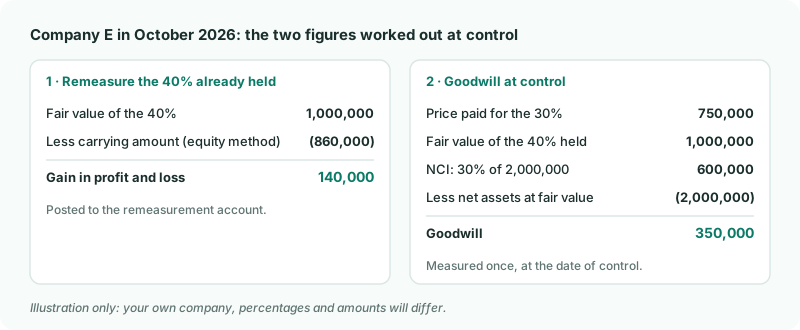
| Remeasurement gain | Fair value of the 40%, less its carrying amount: 1,000,000 − 860,000 = 140,000. |
|---|---|
| Goodwill | The price paid, plus the fair value of the 40%, plus the NCI, less the net assets: 750,000 + 1,000,000 + 600,000 (30% of 2,000,000) − 2,000,000 = 350,000. |
5Complete the acquisition details
- Open Totals and accounts for this company for Company E.
- Choose the group accounts for Investment in subsidiary and Goodwill, and click Save.
Check
The company shows a Current NCI % of 100% less the group’s new share, with no amber dot in Group structure. Under Totals and accounts for this company, Acquisition goodwill equals the price paid plus the fair value of the stake already held plus the NCI, less the net assets you entered.
6Check the result
- Open Reports → Profit & Loss for Oct-2026. The 140,000 remeasurement gain is on its account, and Company E’s revenue and costs appear from October.
- Open Reports → Balance Sheet with Show Entities on. From October, Company E’s assets and liabilities are in, the investment in the associate is gone, and goodwill and NCI appear.
- Open Ownership & Equity → NCI Report for Oct-2026: Company E’s NCI % now is 30%.
Check
The remeasurement gain on the Profit & Loss equals the fair value you entered for the stake already held, less the Associate/JV - investment balance on the Balance Sheet for the month before. From the month of control, that investment balance is gone, the goodwill line equals the acquisition goodwill on the ownership record, and the Balance Sheet balances.
For September and earlier, Company E is still shown the old way — as the group’s 40% share — so the comparatives are not restated.
7If something does not look right
| What you see | What to do |
|---|---|
| The dialog does not ask about the stake already held | The earlier 40% is not recorded, or not as JV / Associate. Check Share purchases and sales and add or correct it. |
| Company E has an amber dot | Open it to see what it Needs. Usually the Gain/loss remeasuring the stake already held account, or one of its own accounts under Totals and accounts for this company, is missing. |
| The remeasurement gain looks wrong | Check the fair value of the old stake, and the balance on Associate/JV - investment on the Balance Sheet for Sep-2026. The gain is the difference between the two. |
| Company E is consolidated before October | The earlier record is set to Subsidiary. Edit it to JV / Associate. |
| The dialog asks for the carrying amount and account of the stake already held | No equity-method entries have been posted for the 40% before October. Enter its carrying amount and the account it is carried in, or post the equity method first: check Associate/JV - investment is chosen in Posting accounts. |
Want more detail? See the documentation