
Foundations · Track 3 · Tutorial 4 of 6
Sell a controlling stake
When the group sells enough of a subsidiary to lose control, the company stops being consolidated, the stake kept is revalued, and a gain or loss is recognised. Record the sale once, and BrizoConsol handles all three.
1Understand what changes when control is lost
In the running example the group has owned 80% of Company B since January 2025, with goodwill of 40,000 (see Account for minority shareholders). In October 2026 it sells 50% for 350,000 and keeps 30%, which gives it significant influence but not control. The 30% kept is worth 210,000.
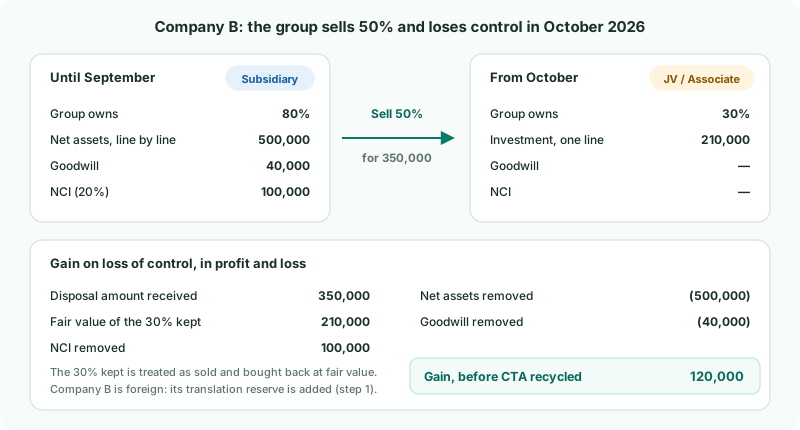
| Until September | Company B is consolidated line by line, with goodwill and 20% NCI. |
|---|---|
| In October | Its net assets, goodwill and NCI leave the group accounts. The 30% kept is treated as if sold and bought back at fair value, so the gain or loss covers the whole stake, not only the 50% sold. |
| Translation reserve | Company B is a foreign company (see Handle foreign currency companies). The group’s share of its translation reserve built up since the group took control — including the exchange differences on its goodwill — moves out of equity and into the gain or loss. The NCI’s share is removed with the NCI and is not recycled. |
| From October | Company B is a JV / Associate. Its figures are no longer consolidated; BrizoConsol posts the group’s 30% share of its profit as JV entries. |
2Choose the disposal account
- Open Ownership & Equity → Ownership, and open NCI account setup with the NCI account settings icon.
- Choose a profit and loss account for Disposal gain/loss (loss of control), and click Save.
- Click Company B, open the Acquisition details tab, and check Investment in subsidiary and Acquisition bank account are chosen.
The gain or loss is posted to the disposal account. The investment account is where the group’s original cost is cleared from, and the bank account receives the proceeds.
3Record the sale
- On Company B’s Ownership history tab, click + Add record.
- Choose your group, Dispose, Oct-2026 and 50.
- Choose JV / Associate as the relationship. This is what tells BrizoConsol control is lost.
- Enter the Disposal amount (350,000).
- Enter the Retained interest fair value (210,000), and choose the Retained interest account the 30% will be carried in.
- Check the notice says the disposal changes control, and click Add Record.
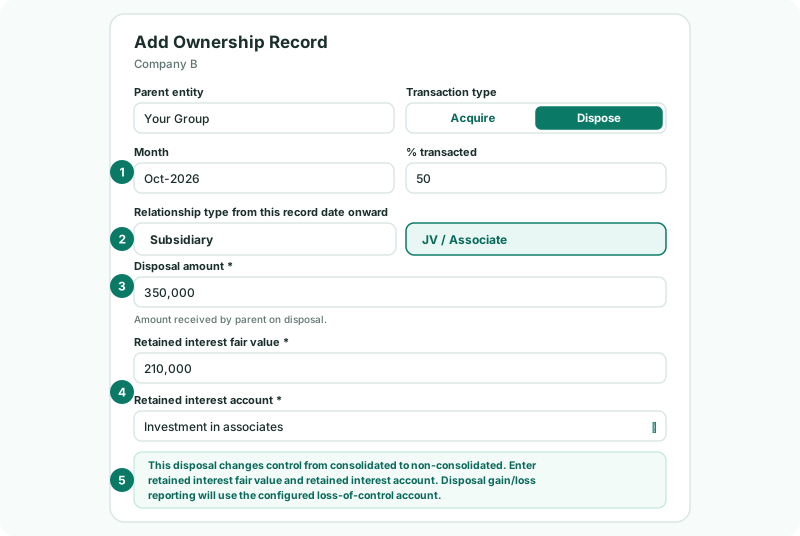
| Disposal amount | What the buyer paid for the 50%, in the group currency. |
|---|---|
| Retained interest fair value | What the 30% kept is worth at the date of the sale — usually from the same valuation as the sale price. It becomes the starting value of the investment. |
| Retained interest account | The investment account the 30% sits in from October, for example an investment in associates account. |
If the notice starts with Warning, the Disposal gain/loss (loss of control) account is not set. You can save the record, but go back to step 2 before you report.
4Check the record
There is nothing to post: saving the record recalculates the group and posts the entries.
Check
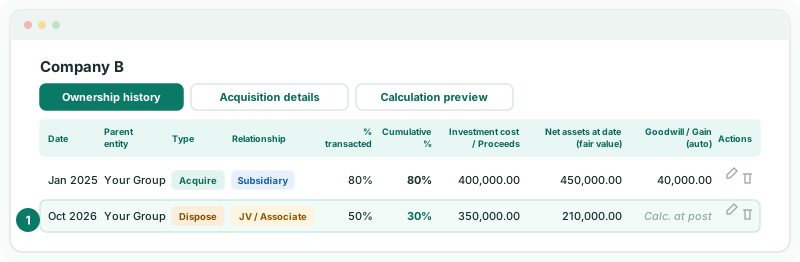
The new row shows Dispose, JV / Associate and a Cumulative % of 30%. Net assets at date (fair value) shows the 210,000 you entered for the stake kept, and Goodwill / Gain (auto) shows Calc. at post — the gain is worked out when the entries are posted.
5Check the result
- Open Reports → Profit & Loss for Oct-2026. The gain is on the Disposal gain/loss (loss of control) account — the 120,000 plus or minus the recycled translation reserve — and Company B’s revenue and costs are included up to September only.
- Open Reports → Balance Sheet with Show Entities on. From October, Company B’s assets and liabilities, its goodwill and its NCI are gone, and the retained interest account shows 210,000.
- Open Ownership & Equity → NCI Report for Company B and Oct-2026. The Disposal (Loss of Control) rows show each balance removed and where it was posted, including Disposal (Loss of Control) - Owners CTA Recycling for the translation reserve.
- Open Ownership & Equity → JV / Associate Report for Company B to see the group’s 30% share of its profit from October.
For September and earlier, Company B is still shown line by line, so the comparatives are not restated.
6If something does not look right
| What you see | What to do |
|---|---|
| The dialog does not ask for the retained interest | The relationship is still Subsidiary. Choose JV / Associate if the group no longer controls Company B. If it does, see Buy out or sell to minority shareholders. |
| Loss-of-control disposal requires a disposal gain/loss P&L account… | Choose the Disposal gain/loss (loss of control) account in NCI account setup. |
| Investment account must be configured for loss-of-control disposal… | Choose Investment in subsidiary on Company B’s Acquisition details tab. |
| Acquisition bank account must be configured for disposal posting… | Choose the Acquisition bank account on the same tab. |
| Missing closing exchange rate for the retranslation of goodwill… | Add the closing rate for Company B’s currency for the month named in the message. Every month since the group took control needs one. |
| The gain looks wrong | Check the Disposal amount and Retained interest fair value — both are in the group currency — and the Owners CTA Recycling row in the NCI Report. |
| Company B is dropped from the wrong month | Edit the record’s Month. Company B stops being consolidated from that month. |
Want more detail? See the documentation