
Retail Chains · Track 2 · Tutorial 1 of 2
Buy a retail chain mid-year
When a group buys a retail chain partway through the year, only the profit after the purchase is the group’s, and the chain’s brand, fit-outs and stock come in at fair value. BrizoConsol posts the acquisition from one ownership record; the allocation to specific assets is a journal.
1Know what changes at the purchase
On 1 July 2026 Your Group buys 80% of Northgate Stores, a chain of shops, for 4,000,000. Both have a December year end. On that date Northgate’s books show net assets of 3,750,000, including its profit for January to June.
| Until June | Northgate isn’t the group’s. Its profit for January to June is part of what the group bought, not profit the group earned. |
|---|---|
| On 1 July | Northgate’s identifiable assets and liabilities are measured at fair value (IFRS 3.18). The difference to the price, after the NCI, is goodwill. |
| From July | Northgate is consolidated line by line, with 20% NCI. |
The purchase price allocation for a retail chain usually values items that aren’t on its books, or are on them at another amount:
| Item | At fair value | In the example |
|---|---|---|
| The brand | An intangible asset of its own | 600,000 |
| Store fit-outs | Their fair value, not their depreciated cost | 300,000 more |
| Stock | Selling price less the costs and profit still to come | 100,000 more |
| Store leases | Northgate’s lease liabilities remeasured at the date, with the right-of-use assets adjusted for leases on better or worse terms than the market (IFRS 3.28B) | No change |
| Deferred tax | On the uplifts, at 25% | 250,000 |
So the net assets at fair value are 3,750,000 + 1,000,000 − 250,000 = 4,500,000.
2Bring Northgate in
Add Northgate to your hierarchy, load its months from January 2026, and map its accounts, as in Buy a new subsidiary. The months before July are needed: the January to June profit can only be taken out of group profit if it is loaded.
3Record the purchase
- Open Ownership & Equity → Ownership, and click Northgate Stores under Group structure.
- Under Share purchases and sales, click + Record, and choose Bought shares.
- Keep Your Group as Parent entity. Choose July 2026 as Month, and enter 80 in % transacted.
- Choose Subsidiary under Relationship type from this record date onward.
- Enter 4,000,000 as Investment cost (group currency) and 4,500,000 as Net assets at date (fair value).
- Keep NCI measurement at Share of net assets (partial goodwill), or choose Fair value of NCI (full goodwill) and enter the NCI fair value. IFRS allows either for each acquisition.
- Click Add Record.
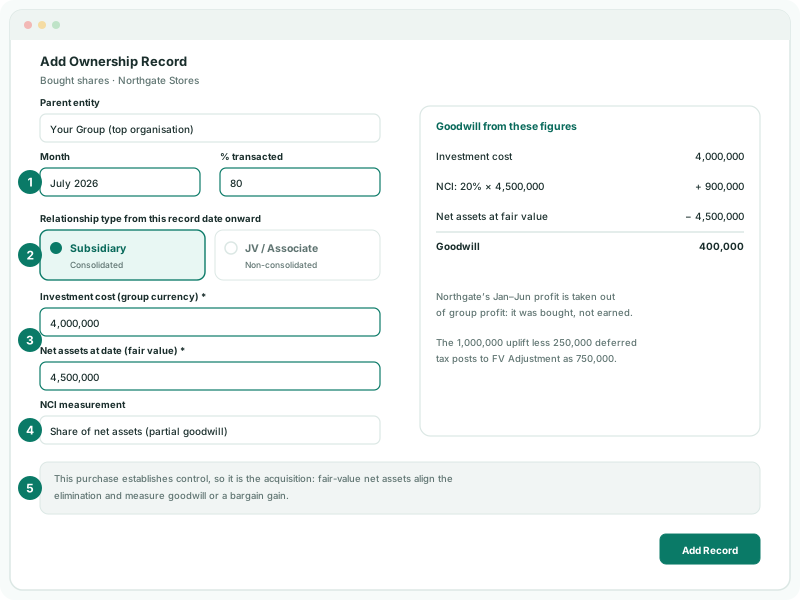
Both amounts are in the group currency and are not converted. BrizoConsol works out goodwill: 4,000,000 + 900,000 NCI − 4,500,000 = 400,000. The month you choose is the first month Northgate is in the group’s profit.
4Choose the accounts
- On Northgate’s page, open Totals and accounts for this company. Choose the accounts for Investment in subsidiary - Northgate Stores and Goodwill - Northgate Stores, and click Save.
- Click the Posting accounts icon beside Group structure. Under Still to choose, choose an account for each, including FV Adjustment, NCI - net assets and NCI - share of profit, and click Save.
Posting accounts lists only the accounts your records use. Saving the record and the accounts queues the acquisition entry for posting, dated July 2026.
5Allocate the fair value adjustment
BrizoConsol posts the whole difference between the fair value and Northgate’s books — here 750,000 — to the FV Adjustment account, as one non-current asset. Reclassify it to the assets it belongs to with a journal:
- Open Adjustments → Consolidation Journals, choose Jul-2026, and click Add a new journal entry.
- Choose Acquisition as Journal Type, and enter a Description such as “Northgate purchase price allocation”.
- Under Debit Lines: Brand 600,000, Store fit-outs 300,000, Inventory 100,000. Under Credit Lines: Deferred tax liability 250,000, FV Adjustment 750,000.
- Click Confirm.
After the purchase the uplifts follow the assets. Depreciate the fit-out uplift over the fit-outs’ remaining life with a recurring journal, and release the stock uplift to cost of sales as the stock is sold. A brand with an indefinite life isn’t amortised; it is tested for impairment every year.
BrizoConsol works out the NCI’s share of profit from Northgate’s own figures, so the extra depreciation in group journals isn’t in it. Post the NCI’s 20% of it with a Consolidation Journal of type NCI.
6Check the result
- On Northgate’s page, the July 2026 record shows Bought 80%, with Price 4,000,000, Net assets at fair value 4,500,000 and Goodwill 400,000, and Northgate shows as Subsidiary with NCI % 20%.
- Open Review → Elim. & Journals Report for Jul-2026, and search for NCI-AUTO-ACQ. The acquisition entry eliminates Northgate’s equity and its January to June profit, and posts the FV adjustment, the investment, the NCI and the goodwill. See Read the acquisition entries line by line.
Check
On Reports → Profit & Loss for Jul-2026, year to date, Northgate’s revenue and costs are in the group from July only. On the Balance Sheet, goodwill is 400,000, NCI starts at 900,000, and the brand, fit-outs and stock carry the uplifts from your journal.
7If something goes wrong
| Net assets at date (fair value) is required for the acquisition that establishes control. | Enter Northgate’s net assets at fair value, in the group currency. |
|---|---|
| Investment cost is required for acquisition. | Enter the price paid for the 80%. |
| NCI posting for this subsidiary is on hold until these acquisitions are completed. | Click Enter figures on the record named, and fill in what it needs. |
| A Needs strip under the record | An account the acquisition posts to isn’t chosen. Click Choose. |
| Group profit includes Northgate before July | The record’s Month is earlier than July. Edit the record. |
| The FV adjustment is larger than the uplift less deferred tax | Northgate’s months up to June aren’t all loaded, so less equity is eliminated. Load them. |
Want more detail? See the documentation