
Retail Chains · Track 2 · Tutorial 2 of 2
Sell a retail chain
When the group sells its stake in a part-owned chain, the chain and its minority leave the group together. The group’s gain is measured against the net assets it carried, less the minority’s share, so the profit it already reported isn’t counted twice.
1Know why the two gains differ
In January 2024 Your Group and a franchise partner set up Southpoint Stores with 1,500,000 of share capital: Your Group put in 1,050,000 for 70%, the partner 450,000 for 30%. The chain has since made 500,000 of profit, so its net assets are 2,000,000, and the NCI, the partner’s 30%, is 600,000.
In October 2026 Your Group sells its whole 70% to the partner for 2,100,000. The partner now owns the chain outright.
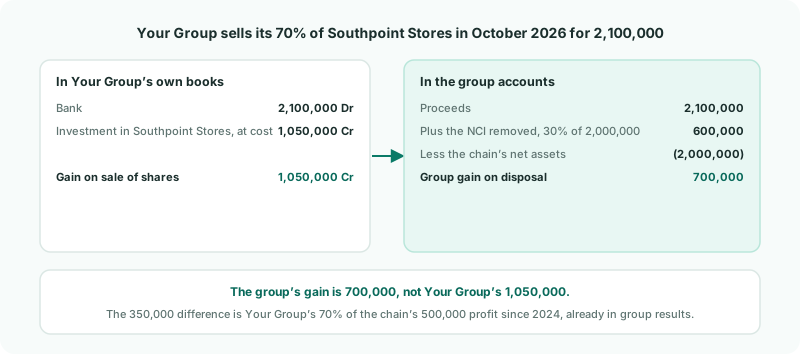
| Your Group’s own gain | Proceeds less its cost: 2,100,000 − 1,050,000 = 1,050,000. |
|---|---|
| The group’s gain | The group carried all of the chain’s net assets, with the partner’s share shown as NCI. Proceeds plus the NCI removed, less the net assets: 2,100,000 + 600,000 − 2,000,000 = 700,000. |
| The difference | Your Group’s 70% of the 500,000 profit since 2024, 350,000, which the group has already reported. |
2Check the accounts
- Open Ownership & Equity → Ownership, and open Posting accounts with the gear beside Group structure.
- Choose a profit and loss account for Disposal gain/loss (loss of control): the group’s gain goes here.
- Choose the account Your Group records its own gain on selling shares in for Parent's gain/loss on sale of shares (P&L), and click Save.
- Click Southpoint Stores, open Totals and accounts for this company, and check Investment in subsidiary is chosen.
Record the sale in Your Group’s own books with its gain on the parent’s gain/loss account. BrizoConsol takes that gain back out of group profit and posts the group’s own gain instead.
3Record the sale
- Beside Southpoint Stores’s Share purchases and sales, click + Record, then Sold shares.
- Keep Your Group as the parent, and choose Oct-2026 and 70.
- Enter the Disposal amount, 2,100,000, and click Add Record.
Selling the whole holding leaves nothing to classify, so the dialog doesn’t ask for a relationship or a retained interest. Its notice reads: This sale disposes of the whole holding, so control is lost and nothing is retained. Southpoint Stores is consolidated up to the month before Oct-2026.
4Read the group gain
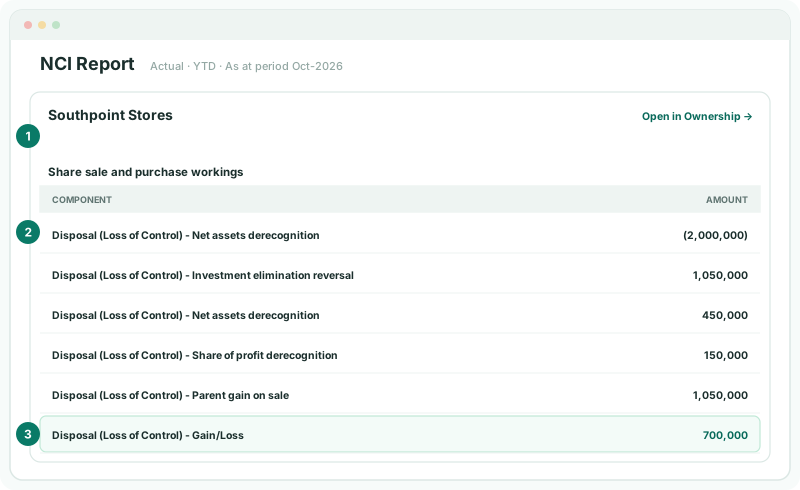
There is nothing to post: saving the record recalculates the group and posts the entries. Open Ownership & Equity → NCI Report, choose Oct-2026, and click Southpoint Stores’s row.
| Row | What it is | Amount |
|---|---|---|
| Disposal (Loss of Control) - Net assets derecognition | The chain’s net assets leave the group. | (2,000,000) |
| Disposal (Loss of Control) - Investment elimination reversal | Your Group’s 1,050,000 cost is put back so the sale in Your Group’s books can clear it. | 1,050,000 |
| Disposal (Loss of Control) - Net assets derecognition | The NCI at the start: the partner’s 30% of 1,500,000. | 450,000 |
| Disposal (Loss of Control) - Share of profit derecognition | The partner’s 30% of the profit since: the rest of the NCI. | 150,000 |
| Disposal (Loss of Control) - Parent gain on sale | Your Group’s own 1,050,000 gain, taken out of group profit. | 1,050,000 |
| Disposal (Loss of Control) - Gain/Loss | The group’s gain, on the Disposal gain/loss (loss of control) account. | 700,000 |
The two Net assets derecognition rows are different accounts: the first is the chain’s own net assets, the second the NCI’s.
Check
On Reports → Profit & Loss for Oct-2026, Disposal gain/loss (loss of control) is 700,000, and the chain’s sales are in the group up to September. On Reports → Balance Sheet for Oct-2026, the chain’s stores, stock and leases, and the NCI, are gone.
5If something goes wrong
| What you see | What to do |
|---|---|
| Loss-of-control disposal requires a disposal gain/loss P&L account in Posting accounts on the Ownership page. | Choose Disposal gain/loss (loss of control) in Posting accounts. |
| Select the account the parent posts its gain or loss on the sale of shares to, in Posting accounts on the Ownership page. | Choose Parent's gain/loss on sale of shares (P&L) in Posting accounts. |
| Investment account must be configured for loss-of-control disposal carrying amount derecognition. | Choose Investment in subsidiary under Southpoint Stores’s Totals and accounts for this company. |
| Disposal proceeds are required. | Enter the Disposal amount on the Sold record. |
| The group gain is the same as Your Group’s own gain | Check the parent’s gain is recorded on the account chosen as Parent's gain/loss on sale of shares (P&L): that is the account BrizoConsol takes it out of. |
Want more detail? See the documentation