
Property Groups · Track 2 · Tutorial 1 of 2
Buy a property SPV mid-year
A property SPV bought part-way through the year joins the group from the month of the purchase, and the price paid has to land on the building, not on one adjustment line. Whether the purchase is a business or an asset decides whether there is goodwill and deferred tax.
1Decide whether you bought a business
On 1 July 2026, Your Group buys 100% of Marina SPV for 5,000,000. Its only asset is a let office building. The group’s financial year runs January to December.
Buying the shares of an SPV is not always a business combination. IFRS 3 lets you apply a concentration test: if substantially all of the fair value of the gross assets bought is in one building, or a group of similar buildings, what you bought is not a business, and the purchase is an asset acquisition. If not, assess whether the SPV comes with processes, such as its own leasing and management staff.
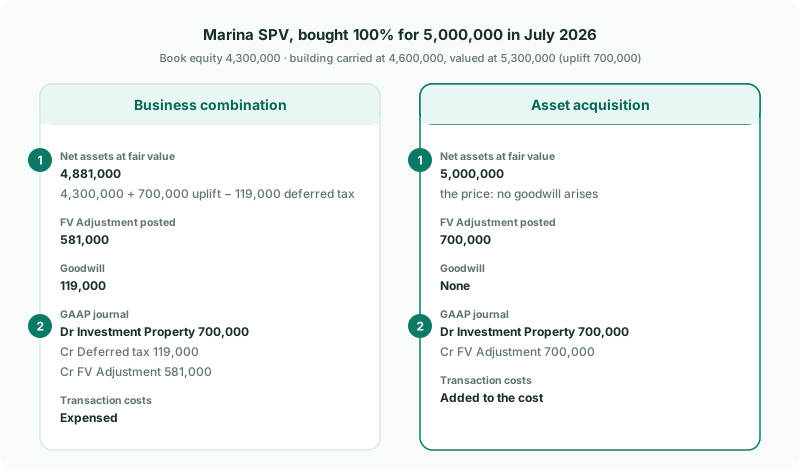
| Business combination | Asset acquisition | |
|---|---|---|
| Goodwill | The excess of the price over the net assets at fair value. | None: the price is allocated to the assets and liabilities by their relative fair values. |
| Deferred tax on the uplift | Recognised. | Not recognised: the initial recognition exemption in IAS 12 applies. |
| Transaction costs | Expensed. | Part of the cost. |
2Bring in the SPV’s figures
Add Marina SPV to your hierarchy, load its months and map its accounts, as in steps 2 to 4 of Buy a new subsidiary. Load every month from January: its profit for January to June is taken out of the group’s figures as earned before the purchase, and a missing month makes the fair value adjustment wrong.
At 30 June, Marina SPV’s books show share capital of 4,000,000, retained earnings brought forward of 150,000 and profit for January to June of 150,000: equity of 4,300,000. The building is carried at 4,600,000; the valuer puts it at 5,300,000.
3Record the purchase
- Open Ownership & Equity → Ownership, and click Marina SPV in Group structure.
- Click + Record, and choose Bought shares.
- Choose Your Group as Parent entity, Jul-2026 as the Month, 100 in % transacted, and Subsidiary.
- Enter the Investment cost (group currency) and the Net assets at date (fair value) for your route, below, and click Add Record.
| Field | Business combination | Asset acquisition |
|---|---|---|
| Investment cost (group currency) | 5,000,000, the price. Leave transaction costs out. | 5,000,000, plus any transaction costs. |
| Net assets at date (fair value) | 4,881,000: book equity 4,300,000, plus the 700,000 uplift, less deferred tax of 119,000 at 17%. | The same as the investment cost, 5,000,000. |
BrizoConsol has no separate setting for an asset acquisition. Entering the cost as the net assets makes the goodwill nil, and puts the whole difference between the cost and the SPV’s book equity on the FV Adjustment account, ready to allocate in step 5.
The note under the amounts reads This purchase establishes control, so it is the acquisition. The record shows Bought 100% and control gained.
4Choose the accounts
- Open Totals and accounts for this company. Choose Investment in subsidiary - Marina SPV, the account Your Group’s books hold the cost in, and, for a business combination, Goodwill - Marina SPV. Click Save.
- Click Choose accounts in the banner, choose FV Adjustment and any other account listed, and click Save.
Saving recalculates the group and posts the acquisition, dated July. It eliminates Marina SPV’s equity of 4,150,000 and its January to June profit of 150,000 against the investment, and posts the rest of the investment to FV Adjustment: 700,000 for the asset acquisition, or 581,000 and goodwill of 119,000 for the business combination. The entry is explained line by line in Read the acquisition entries line by line.
5Allocate the uplift to the building
FV Adjustment is one account for the whole group. Move the uplift onto the building, and the deferred tax onto its own line, with a GAAP journal.
- Select Your Group, open Adjustments → GAAP Journals, and click + Add a new journal entry.
- Enter the Journal ID PPA-MARINA-2026-07, the date 31 July 2026, the Journal Type Investment Property, and a Description.
- Enter the lines for your route, and click Confirm.
| Route | Lines |
|---|---|
| Business combination | Dr Investment Property 700,000; Cr Deferred Tax Liability 119,000; Cr FV Adjustment 581,000. |
| Asset acquisition | Dr Investment Property 700,000; Cr FV Adjustment 700,000. |
If the group measures investment property at fair value, the building is then carried at its valuation from July, as in Measure investment property at group level. Under the cost model, depreciate the uplift each month.
GAAP Journals is in the menu once an accounting standard is enabled for the group. Without one, post the same lines on Adjustments → Consolidation Journals with the type Acquisition.
6Check the result
- On Ownership, look at the record for Marina SPV.
- Open Reports → Balance Sheet for Jun-2026 and Jul-2026 with Show Entities on.
- Open Reports → Profit & Loss for Jul-2026, year to date.
Check
The record shows Net assets at fair value as entered and, for a business combination, Goodwill of 119,000. In June, Marina SPV is not in the group column. In July, the building is in the group at 5,300,000, FV Adjustment is nil, and the balance sheet still balances. The year-to-date profit and loss includes Marina SPV’s rent from July only.
7If something goes wrong
| What you see | What to do |
|---|---|
| FV adjustment account must be configured for acquisition posting when fair value net assets differ from source equity balances. | Choose FV Adjustment in Posting accounts. |
| Goodwill account must be configured for acquisition posting with positive goodwill. | Choose Goodwill - Marina SPV under Totals and accounts for this company. |
| NCI posting for this subsidiary is on hold until these acquisitions are completed. | Click Enter figures beside the record, and enter what it names. |
| Goodwill appears on an asset acquisition | The net assets entered are below the investment cost. Enter the same amount in both. |
| Marina SPV’s January to June profit is in the group | The record’s Month is earlier than July, or its months aren’t all loaded. Check both. |
| FV Adjustment isn’t nil after the journal | The journal’s FV Adjustment line differs from the amount posted. Check it against the acquisition entry. |
Want more detail? See the documentation