
Property Groups · Track 3 · Tutorial 1 of 1
Measure investment property at group level
Your SPVs may keep their buildings at cost, while the group measures investment property at fair value. Adjust at group level with GAAP journals, so every SPV’s building is on the group’s policy and each valuation reaches profit or loss.
1Know what changes at group level
Your Group measures investment property at fair value under IAS 40. Harbour SPV, wholly owned, keeps its building at cost less depreciation in its own books. A group applies one accounting policy to all its investment property, so the group adjusts Harbour SPV’s figures.
| In Harbour SPV’s books | In the group’s statements | |
|---|---|---|
| The building | Cost less depreciation | Fair value |
| Depreciation | Charged every month | None |
| A change in value | Not recognised | A gain or loss in profit or loss, in the period of the valuation |
If the group uses the cost model instead, Harbour SPV’s figures may already be on its policy: check its depreciation rates and useful lives against the group’s.
A building let to another group company is not investment property in the group’s statements: to the group it is occupied by its owner, so it is property, plant and equipment under IAS 16. If the group’s part of a building is significant and can’t be sold separately, use the journal type PP&E for its adjustments, not Investment Property.
2Bring the building to fair value
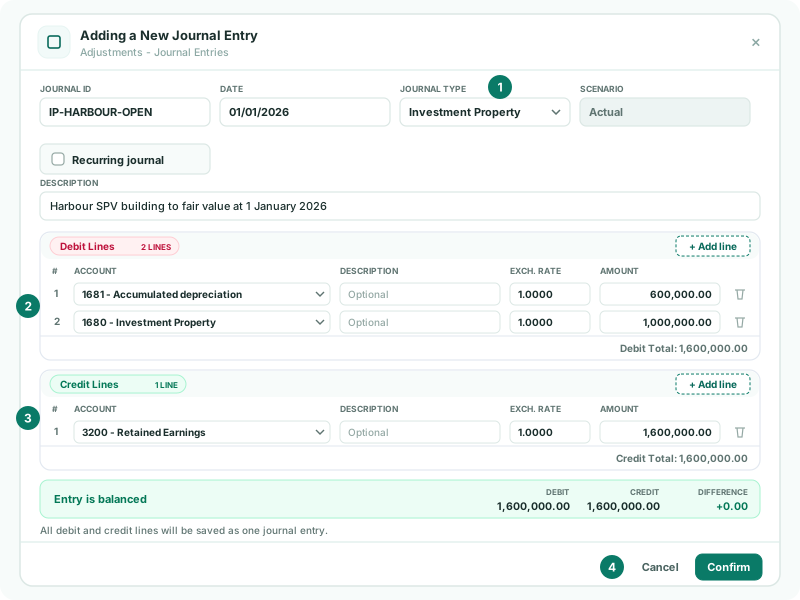
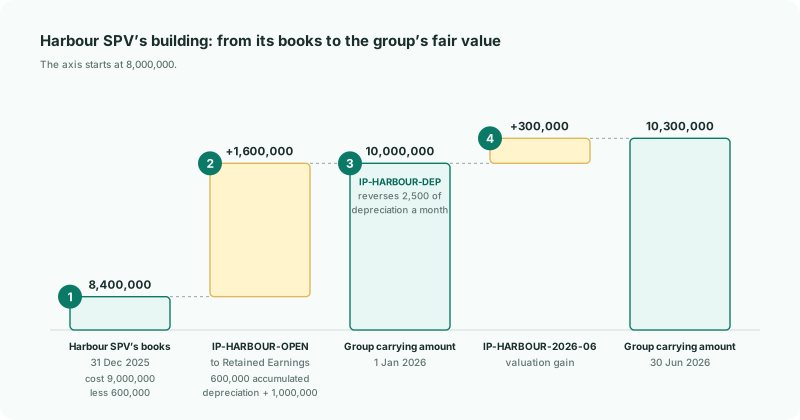
At 31 December 2025, Harbour SPV carries the building at 8,400,000: cost 9,000,000 less depreciation of 600,000. Its fair value is 10,000,000. The 1,600,000 difference belongs to earlier years, so it goes to retained earnings, once.
- Select Your Group, open Adjustments → GAAP Journals, and click + Add a new journal entry.
- Enter the Journal ID IP-HARBOUR-OPEN, the date 1 January 2026, the Journal Type Investment Property, and a Description.
- Debit the building’s accumulated depreciation 600,000 and Investment Property 1,000,000, credit Retained Earnings 1,600,000, and click Confirm.
GAAP Journals is in the menu once IFRS is enabled for the group; see Switch on IFRS and classify equity. Recognise deferred tax on the difference where the group’s tax position gives rise to it: for investment property at fair value, IAS 12 measures it presuming the property is recovered through sale.
3Take out the depreciation every month
- Add a journal with the Journal ID IP-HARBOUR-DEP, type Investment Property, and its description.
- Tick Recurring journal, and choose Jan-2026 as Start Period and Dec-2026 as End Period.
- Debit the accumulated depreciation 2,500, credit Depreciation 2,500, Harbour SPV’s monthly charge, and click Confirm.
The group carrying amount then stays at 10,000,000 until the next valuation.
4Post each valuation
At 30 June 2026 the building is valued at 10,300,000: 300,000 above the group carrying amount.
- Add a journal with the Journal ID IP-HARBOUR-2026-06, the date 30 June 2026, type Investment Property, and a description that names the valuation.
- Debit Investment Property 300,000, credit your fair value gains on investment property account 300,000, and click Confirm.
A fall in value is the same entry the other way round, to the same account. Post the deferred tax on the gain with it, if any.
5Check the building
- On GAAP Journals, type IP-HARBOUR in the search box.
- Open Reports → Balance Sheet for Jun-2026, and drill into Investment Property and its accumulated depreciation.
- Open Reports → Profit & Loss for Jun-2026, year to date.
Check
The building is carried at 10,300,000 in the group: Harbour SPV’s cost and depreciation plus the journals. Its depreciation for January to June is nil in the group column, and the 300,000 gain is in profit or loss.
6If something goes wrong
| What you see | What to do |
|---|---|
| GAAP Journals isn’t under Adjustments | No accounting standard is enabled for the group. Enable IFRS on the Accounting Standard page. |
| Depreciation still shows in the group | The recurring journal doesn’t cover the month, or its amount differs from Harbour SPV’s charge. Edit the recurring series. |
| Journal ID already exists: … | Each Journal ID can be used once. Add the month, as in IP-HARBOUR-2026-12. |
| Recurring journal end period must be on or after the start period. | Choose an End Period after the Start Period. |
| The SPV has minority shareholders | The NCI is worked out from the SPV’s own figures, so it doesn’t include these group journals. Post the NCI’s share as a manual NCI journal, as in Reconcile the NCI and associate entries. |
| One or more selected periods are locked. | The month is locked. Ask an administrator to unlock it, or post in an open month. |
Want more detail? See the documentation