
US GAAP Groups · Track 3 · Tutorial 1 of 4
Read the balance sheets and profit and loss
Available on ProPremium
The US GAAP balance sheets and profit and loss show the same consolidated figures as the Base Balance Sheet and Profit & Loss, laid out the US GAAP way. Most lines come from account sections; stockholders’ equity and the operating expense breakdown come from the classifications you set.
1Know where the lines come from
| From the account sections | Assets, liabilities, revenue, cost of goods sold, operating expenses, interest, other income and expense, and tax. Each line adds up the accounts in a section of the Common COA, such as Bank or Non-Current Liability. Nothing to classify. |
|---|---|
| From your classifications | Every stockholders’ equity line, the AOCI components, Non-Controlling Interests, and the Selling, General and Administrative, and Research and Development breakdown of operating expenses. Each reads the accounts you put on it on the Accounting Standard page. |
| Worked out | Subtotals, and the lines that are the rest of a section: Other Non-Current Assets and Other Non-Operating Items. |
The figures are the one consolidation, so the US GAAP statements agree with the Base reports. Where they don’t, an equity classification is missing, or a revaluation reserve is still there.
2Read the balance sheets
- Select Your Group, and open Reports → All Reports → Consolidated Balance Sheets.
- Choose the month. The statement shows the balances at the end of it.
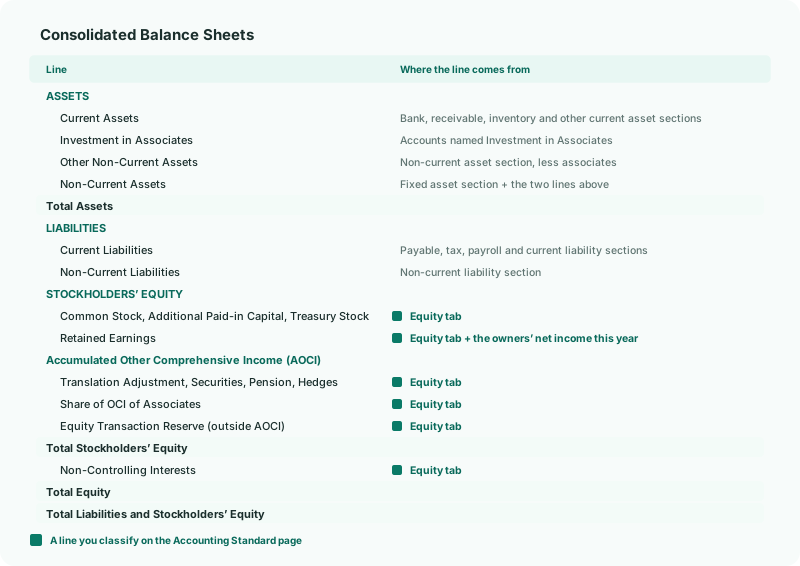
| Non-Current Assets | Property, plant and equipment is part of this line, with Investment in Associates and Other Non-Current Assets. |
|---|---|
| Investment in Associates | The accounts named Investment in Associates or Investment in Joint Ventures, taken out of Other Non-Current Assets. See Account for associates and joint ventures. |
| Treasury Stock | The accounts on the Treasury Shares line — the company’s own shares it has bought back. Their debit balance reduces stockholders’ equity. |
| Retained Earnings | The accounts on the Retained Earnings line plus the year’s net income so far that belongs to the owners. The NCI’s share is in Non-Controlling Interests. |
| Accumulated Other Comprehensive Income (AOCI) | Its components, each from its line on the Equity tab: Foreign Currency Translation Adjustment, Unrealised Gains/Losses on Securities, Pension Adjustments, Cash Flow Hedge Gains/Losses, and Share of OCI of Associates. |
| Foreign Currency Translation Adjustment | The owners’ share of the CTA. The NCI’s share is in Non-Controlling Interests. |
| Equity Transaction Reserve | Where the difference goes when the group buys or sells shares in a subsidiary it keeps control of. It is part of stockholders’ equity but not of AOCI: it isn’t comprehensive income. |
| Total Stockholders’ Equity | Every line above added together: the owners’ equity. |
| Non-Controlling Interests | The accounts on the Non-Controlling Interest line. Accounts created in Posting accounts are classified from their names, so NCI Net Assets, NCI Share of Profit, NCI Share of CTA and NCI Share of Other Reserves all land here. |
3Read the profit and loss
- Open Reports → All Reports → Consolidated Statements of Operations for 2026.
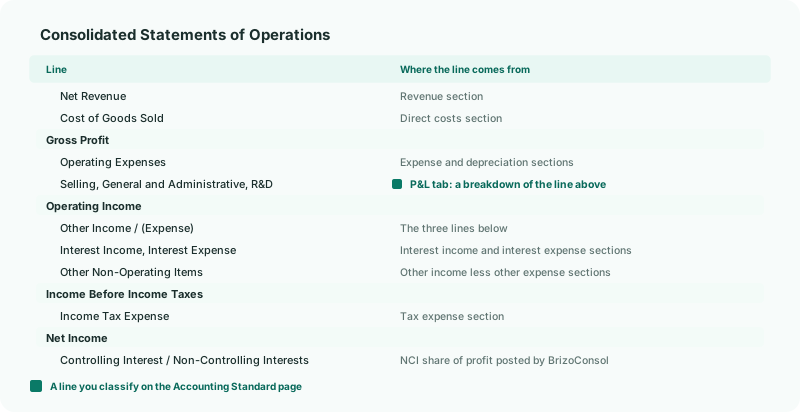
| Operating Expenses | The expense and depreciation sections. Selling Expenses, General and Administrative Expenses and Research and Development under it show the accounts you classified: for Your Group, 310,000 and 930,000 of the 1,240,000. |
|---|---|
| Other Income / (Expense) | Interest income less interest expense, plus Other Non-Operating Items. It comes after Operating Income, so interest and other income don’t change operating income. |
| Other Non-Operating Items | The other income section less the other expense section. The group’s share of an associate’s profit is here. |
| Controlling Interest, Non-Controlling Interests | Under Net Income Attributable to. The NCI’s share is the share of profit BrizoConsol posts for each subsidiary with an NCI; the controlling interest is the rest. |
4Check against the Base reports
- Open the group’s Balance Sheet and Profit & Loss for the same month and year.
Check
On the US GAAP balance sheets, Total Liabilities and Stockholders’ Equity equals Total Assets, and Total Equity equals the Balance Sheet’s equity — 1,767,100 for Your Group once the revaluation is reversed. Net Income on the US GAAP profit and loss equals Net Profit on Profit & Loss.
5If something goes wrong
| Total Equity is lower than the Balance Sheet, and the statement doesn’t balance | An equity account isn’t classified, or a revaluation reserve hasn’t been reversed. See Switch on US GAAP and classify equity. |
| Selling, G&A and R&D don’t add up to Operating Expenses | Some expense or depreciation accounts aren’t classified. See Classify profit and loss and cash flow lines. |
| Investment in Associates is empty, but the group has an associate | The investment account’s name wasn’t recognised. Create it from Posting accounts on the Ownership page, named Investment in Associates. |
| The US GAAP statements aren’t in All Reports | Select the group, not a company. US GAAP must be enabled and saved for it. |
Want more detail? See the documentation