
US GAAP Groups · Track 3 · Tutorial 2 of 4
Read the statement of comprehensive income
Available on ProPremium
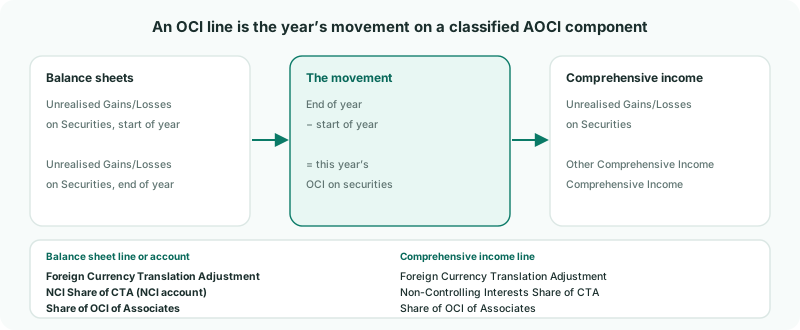
The US GAAP statement of comprehensive income starts from net income and adds other comprehensive income: the gains and losses that go to accumulated other comprehensive income (AOCI) instead of the profit and loss. Each line is the year’s movement on one AOCI component.
1Know how the statement is built
| Net Income | The group’s net income, then split between Controlling Interest and Non-Controlling Interests, as on the US GAAP profit and loss. |
|---|---|
| The OCI lines | Each is the movement in the period on one AOCI component, or on one of the NCI accounts that hold the NCI’s share of them. |
| Comprehensive Income | Net income plus other comprehensive income. |
| Attributable to Controlling Interest | Comprehensive income less the NCI’s part. |
| Attributable to Non-Controlling Interests | The NCI’s share of net income, plus its share of the CTA, plus its share of the other reserves. |
| OCI line | Reads the movement on |
|---|---|
| Share of OCI of Associates | Share of OCI of Associates |
| Foreign Currency Translation Adjustment | Foreign Currency Translation Adjustment — 3500 CTA Reserve for Your Group |
| Unrealised Gains/Losses on Securities | Unrealised Gains/Losses on Securities |
| Pension Adjustments | Pension Adjustments |
| Cash Flow Hedge Gains/Losses | Cash Flow Hedge Gains/Losses |
| Non-Controlling Interests Share of CTA | The NCI share of CTA account — 3620 NCI Share of CTA for Your Group |
| Non-Controlling Interests Share of Other Reserves | The NCI share of other reserves account chosen in Posting accounts |
2Read the other comprehensive income
- Select Your Group, and open Reports → All Reports → Consolidated Statements of Comprehensive Income for 2026.
| Foreign Currency Translation Adjustment | The owners’ part of the difference from translating Company B and Company C: the movement on 3500 CTA Reserve. The NCI’s 20% of Company B’s part, the movement on 3620 NCI Share of CTA, is on its own line, Non-Controlling Interests Share of CTA. |
|---|---|
| Share of OCI of Associates | The group’s share of an associate’s OCI, posted by BrizoConsol — 6,000 for Company G in Account for associates and joint ventures. |
| Securities, pension, hedges | The movement on each component, through the accounts mapped to the classified group account. A line with no account classified shows nothing. When a foreign subsidiary holds securities or hedging gains and losses, the exchange difference from retranslating them isn’t on their line: it is part of the translation adjustment. |
| NCI share of other reserves | The NCI’s share of the movements on those components, posted by BrizoConsol to the NCI share of other reserves account. Shows nothing if the group has no such account, or a partly owned company’s reserves didn’t move. |
Your Group has no revaluation reserve on the US GAAP statements: it was reversed, as in Bring subsidiaries’ local-standard figures onto US GAAP. Under the total, the two attribution lines split comprehensive income: the NCI receives its share of net income, the CTA and the other reserves, and the controlling interest receives the rest.
3Trace each line to its component
- Open Consolidated Statements of Changes in Stockholders’ Equity for 2026.
- Compare each OCI line with the Other Comprehensive Income row of the matching component.
| OCI line | Equals, on the statement of changes in equity |
|---|---|
| Foreign Currency Translation Adjustment, Unrealised Gains/Losses on Securities, Pension Adjustments, Cash Flow Hedge Gains/Losses, Share of OCI of Associates | The OCI row of the component with the same name |
| Non-Controlling Interests Share of CTA and Share of Other Reserves | Non-Controlling Interests’ OCI row, together |
| Other Comprehensive Income | The Total Equity - Other Comprehensive Income row |
Check
Other Comprehensive Income on the statement of comprehensive income equals Total Equity - Other Comprehensive Income on the statement of changes in equity, and Non-Controlling Interests’ OCI row equals its share of the CTA plus its share of the other reserves.
Because a line is the component’s movement, anything posted to it shows on it. Post only OCI to an AOCI account; move amounts between reserves and retained earnings through a journal you can recognise.
4If something goes wrong
| An OCI line is empty, but the account moved | The account isn’t on its equity line. Classify it on the Equity tab of the Accounting Standard page. |
| An OCI line includes something that isn’t OCI | Something other than OCI was posted to the account. Find it in Review → Elim. & Journals Report, and post it to the right account. |
| Share of OCI of Associates is empty | Classify the associate OCI reserve on Share of OCI of Associates, as in Account for associates and joint ventures. |
| A revaluation surplus is missing | US GAAP has none. Reverse the revaluation, as in Bring subsidiaries’ local-standard figures onto US GAAP. |
| Non-Controlling Interests Share of Other Reserves is empty, but a partly owned company’s reserves moved | The group has no NCI share of other reserves account. Choose or create one in Posting accounts, on the Ownership page. |
Want more detail? See the documentation