
SaaS & Technology Groups · Track 2 · Tutorial 2 of 2
Write down deferred revenue on an acquisition
When a SaaS group buys a company that has been paid in advance, the deferred revenue it takes over is measured at fair value, usually far below the books. The difference lowers goodwill, and comes back out of group revenue as the service is delivered.
1Know why deferred revenue is written down
On 1 July 2026 Your Group buys 100% of Company S, a SaaS company, for 3,000,000. On 30 June its books show net assets of 1,800,000, after deferred revenue of 600,000: annual subscriptions its customers paid for in advance, which it will release as revenue from July to December, 100,000 a month.
Under IFRS 3 the deferred revenue is measured at its fair value on the date, like every other liability taken over. What Your Group took over is the obligation to keep delivering the service, not the cash, which Company S already holds. A valuer puts that at the cost to deliver it, 190,000, plus a normal margin, 50,000: 240,000. So the deferred revenue is written down by 360,000.
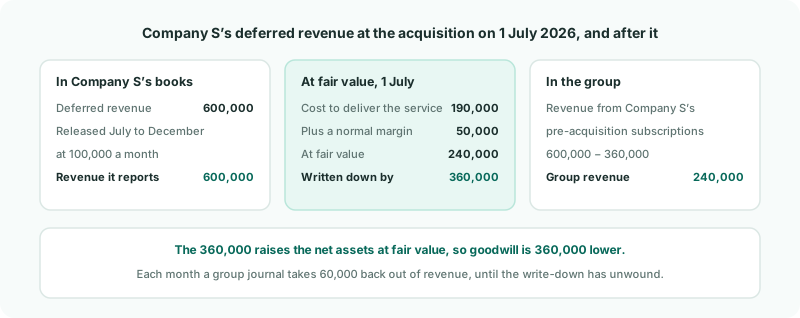
| At the acquisition | The net assets at fair value are 1,800,000 + 360,000 = 2,160,000. Goodwill is 3,000,000 − 2,160,000 = 840,000, not 1,200,000. |
|---|---|
| Afterwards | Company S keeps releasing 600,000 in its own books. The group recognises only the 240,000 it measured, so 60,000 a month comes back out of group revenue until December. |
| Under US GAAP | ASU 2021-08 measures the deferred revenue the acquirer takes over under ASC 606, usually at Company S’s own amount. There is no write-down and nothing to unwind. |
The figures leave out the deferred tax on the write-down to keep them simple.
2Record the acquisition at the written-down net assets
- Open Ownership & Equity → Ownership, and click Company S under Group structure.
- Under Share purchases and sales, click + Record, then Bought shares.
- Choose Your Group, Jul-2026 and 100, and choose Subsidiary.
- Enter 3,000,000 in Investment cost (group currency), and 2,160,000 in Net assets at date (fair value): the books plus the write-down.
- Click Add Record.
BrizoConsol eliminates Company S’s equity as it stands in its books and posts the 360,000 difference to the FV Adjustment account chosen in Posting accounts. That balance is the write-down the group still has to unwind. The full steps for an acquisition are in Record an acquisition and its acquisition details.
Check
Under Company S’s Totals and accounts for this company, Acquisition goodwill is 840,000.00. In Review → Elim. & Journals Report for Jul-2026, the acquisition entry for Company S has a line Auto NCI acquisition FV adjustment - Company S of 360,000.
3Unwind the write-down each month
The write-down unwinds as Company S delivers the service it was paid for: here evenly, 60,000 a month from July to December. Post it once, as a recurring group journal.
- Select Your Group, and open Adjustments → Consolidation Journals for Jul-2026.
- Click Add a new journal entry. Enter a Journal ID such as S-DR-UNWIND, keep Journal Type as Other Consolidation Journals, and enter a Description that says what it is.
- Tick Recurring journal, and choose Jul-2026 as Start Period and Dec-2026 as End Period.
- Under Debit Lines, choose the group’s subscription revenue account and enter 60,000. Under Credit Lines, choose FV Adjustment and enter 60,000.
- When Difference shows +0.00, click Confirm.
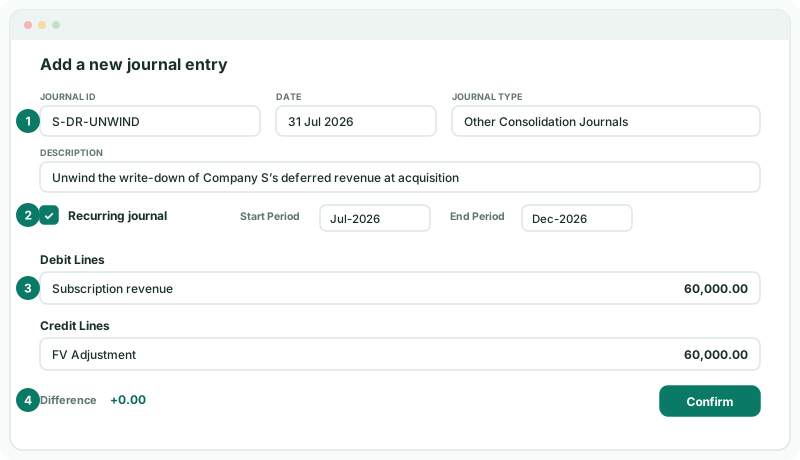
BrizoConsol posts a copy in each month from July to December. If the subscriptions run longer, or are delivered unevenly, use the schedule from the valuation instead: one journal per month with that month’s amount.
4Check the result
| Profit & Loss, Jul–Dec 2026 | With Show Entities on, Company S’s column shows its 600,000 of released revenue; the Elims/Adj column takes 360,000 back out. The group shows 240,000. |
|---|---|
| Balance Sheet, Dec-2026 | FV Adjustment holds nothing for Company S: the 360,000 posted at the acquisition has been cleared by the six journals. |
| Elim. & Journals Report | Each month from July has its S-DR-UNWIND journal, such as S-DR-UNWIND-202607. |
Company S’s own deferred revenue, 2400 Deferred Revenue, is unchanged by any of this: it falls to nil in its own books as it releases the revenue. How the companies’ deferred revenue reaches one group line is in Align deferred revenue across Xero and QuickBooks companies.
5If something goes wrong
| What you see | What to do |
|---|---|
| FV adjustment account must be configured for acquisition posting when fair value net assets differ from source equity balances. | Choose FV Adjustment in Posting accounts. The acquisition needs it whenever the net assets at fair value differ from the books. |
| Goodwill is 1,200,000 | The record has Company S’s book net assets, 1,800,000. Edit it and enter 2,160,000. |
| FV Adjustment still has a balance for Company S in January 2027 | The journals don’t add up to the write-down, or one month is missing. Compare the Elim. & Journals Report for July to December with the 360,000. |
| One or more selected periods are locked. | Start the recurring journal after the last locked month, and post the earlier months one by one. |
Want more detail? See the documentation