
Ownership and NCI · Track 3 · Tutorial 1 of 4
Buy more of a subsidiary you control
When the group buys more of a company it already controls, the NCI it buys leaves at its carrying amount and the difference to the price goes to equity. Follow Company F’s 10% purchase through every figure BrizoConsol posts.
1Know the figures
Your Group bought 80% of Company F in September 2026 for 960,000, with net assets at fair value of 1,000,000: an NCI of 200,000 and goodwill of 160,000 (see Record an acquisition and its acquisition details). Since then BrizoConsol has posted the NCI’s 20% of Company F’s profit, 16,000, so the NCI stands at 216,000.
In December 2026, Your Group buys another 10% of Company F from its minority shareholders for 120,000. Company F stays a subsidiary, now 90% owned.
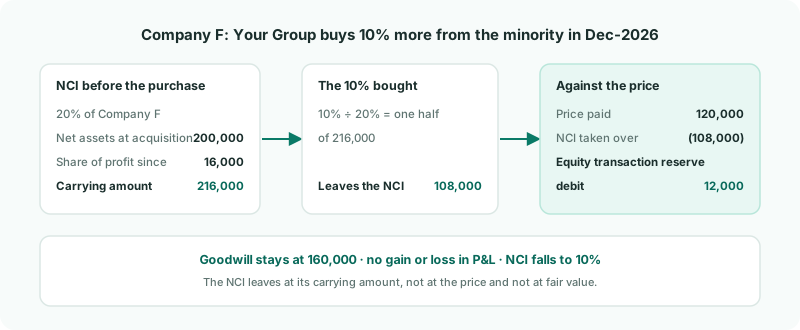
| No new goodwill | Goodwill was measured once, when the group took control. Buying more of a company it already controls isn’t a new acquisition, so goodwill stays at 160,000. |
|---|---|
| No gain or loss | It is a deal between the group’s owners and the minority, so the difference to the price goes to equity, not to profit and loss. |
| What leaves the NCI | The part of the NCI’s carrying amount the group buys: its net assets, its share of profit since the acquisition, its share of the translation reserve and its other reserves. Not the price, and not a new fair value. |
2Choose the reserve account
- Open Ownership & Equity → Ownership, and open Posting accounts with the gear beside Group structure.
- Choose an equity account for Equity transaction reserve, and click Save.
If you leave it empty, BrizoConsol uses the NCI - share of other reserves account instead. Once the record is saved and no reserve is chosen, Still to choose lists it as Company F: bought 10% in Dec 2026 with control already held.
3Record the purchase
- Beside Company F’s Share purchases and sales, click + Record, then Bought shares.
- Keep Your Group (top organisation) as the parent, and choose Dec-2026 and 10.
- Leave the relationship as Subsidiary.
- Enter the Investment cost (group currency), 120,000.
- Check the notice says control is already held, and click Add Record.
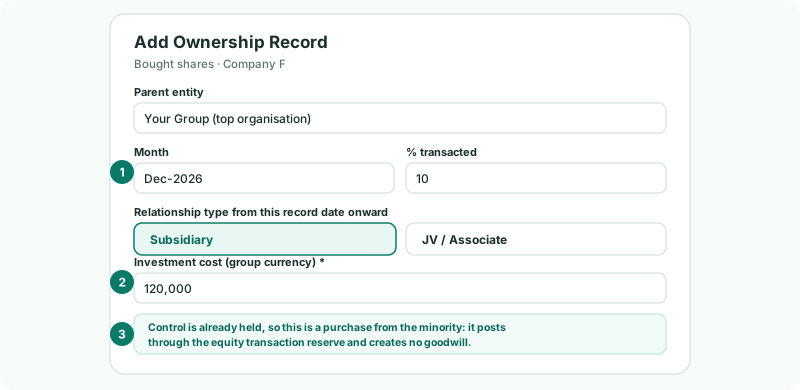
The dialog doesn’t ask for net assets at fair value or for the NCI measurement. Those belong to the purchase that gave control, because they measure goodwill.
Check
The new record reads Bought 10%, control kept and 80% → 90%, and Company F’s NCI % on the Ownership page is now 10%.
4Read the workings
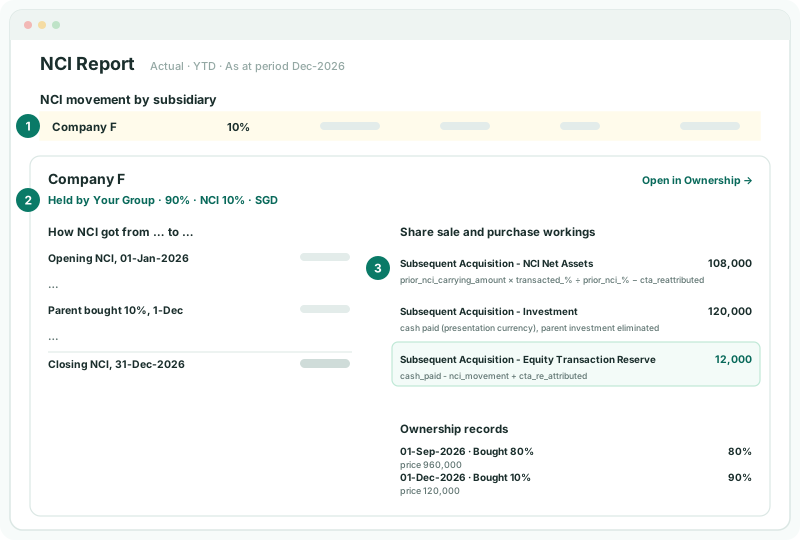
There is nothing to post: saving the record recalculates the NCI and posts the entries. Open Ownership & Equity → NCI Report, choose Dec-2026, and click Company F’s row.
| Row | Formula | Amount |
|---|---|---|
| Subsequent Acquisition - NCI Net Assets | prior_nci_carrying_amount × transacted_% ÷ prior_nci_% − cta_reattributed | 216,000 × 10% ÷ 20% = 108,000 |
| Subsequent Acquisition - Investment | cash paid (presentation currency), parent investment eliminated | 120,000 |
| Subsequent Acquisition - Equity Transaction Reserve | cash_paid - nci_movement + cta_re_attributed | 120,000 − 108,000 = 12,000 |
The carrying amount is the NCI posted for Company F up to the end of the month of the purchase, before this purchase’s own entries. If Company F owns companies of its own, it also includes the part of their NCI that Company F’s minority holds through it.
If no NCI has been posted for Company F yet, the row uses the NCI from the acquisition instead: first_acquisition_nci_amount ÷ first_acquisition_nci_% × transacted_%, here 200,000 ÷ 20% × 10% = 100,000.
5Read the entry
| Account | Debit | Credit |
|---|---|---|
| NCI - net assets | 108,000 | |
| Equity transaction reserve | 12,000 | |
| Investment in subsidiary - Company F | 120,000 | |
| Total | 120,000 | 120,000 |
Your Group recorded the 120,000 in its own books, against its investment in Company F, and the cash has already left its bank. So the entry clears that investment instead of touching the bank. The whole 108,000 is taken off the NCI - net assets line, even though part of it came from the NCI’s share of profit.
Open Review → Elim. & Journals Report for Dec-2026 and search for NCI-AUTO-ACQ. Open Auto NCI subsequent acquisition posting Company F (ACQUIRE). Its lines are Auto NCI net assets movement - subsequent acquisition, Auto NCI equity transaction reserve - subsequent acquisition and Auto NCI investment elimination - subsequent acquisition.
Check
On Reports → Balance Sheet for Dec-2026, goodwill for Company F is still 160,000 and the equity transaction reserve shows the 12,000 debit. On Reports → Profit & Loss, there is no gain or loss on the purchase.
6If Company F reports in another currency
Part of the NCI’s carrying amount is its share of the translation reserve. The half of it the group buys moves to the owners’ CTA reserve, so the entry has two more lines: Auto NCI CTA re-attribution - subsequent acquisition, a debit to NCI - share of CTA, and Auto NCI CTA re-attribution - subsequent acquisition (owners), a credit to the CTA reserve. The NCI net assets line takes the rest of the 108,000, and the reserve entry is adjusted by the same amount. The full example is in Buy, sell or change your stake in a foreign company.
7If something goes wrong
| What you see | What to do |
|---|---|
| NCI other reserves account must be configured as equity transaction reserve for subsequent acquisition/disposal postings. | Neither Equity transaction reserve nor NCI - share of other reserves is chosen. Choose one in Posting accounts. |
| Investment account must be configured for acquisition posting when investment amount exists. | Click Company F, open Totals and accounts for this company, and choose Investment in subsidiary. |
| No CTA reserve account (consolidate_cta) is configured, so the CTA re-attributed to the owners on the subsequent acquisition of Company F has nowhere to go. | Company F is in another currency and the group has no CTA reserve account. Set one up as in Handle foreign currency companies. |
| The dialog asks for net assets at fair value | BrizoConsol thinks this purchase gives control. Check Company F’s earlier record is set to Subsidiary, not JV / Associate. |
| The NCI % changed in the wrong month | Edit the record’s Month. The new % applies from that month. |
Want more detail? See the documentation