
Ownership and NCI · Track 3 · Tutorial 2 of 4
Sell part of a subsidiary and keep control
When the group sells part of a company and still controls it, the parent books a gain but the group does not. Follow Company F’s 10% sale through what the parent records and what BrizoConsol posts.
1Know the figures
Your Group bought 80% of Company F in September 2026 for 960,000. The acquisition posted a fair-value uplift of 80,000 over Company F’s own books (see Read the acquisition entries line by line). At the start of December 2026, Company F’s equity in its own books is 1,000,000.
In December 2026, Your Group sells 10% of Company F to outside investors for 150,000. It keeps 70% and control.
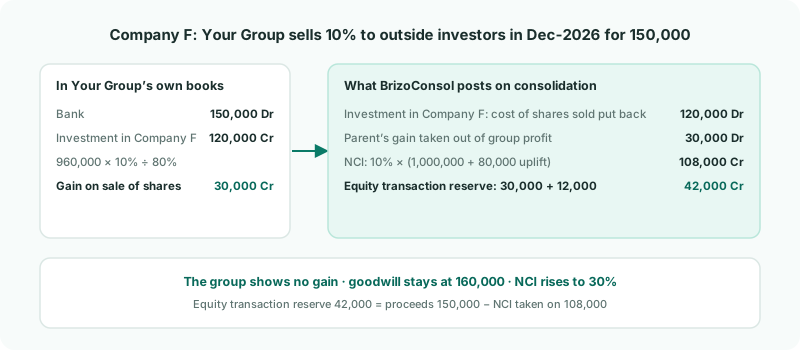
| In Your Group’s books | The sale is a sale: the cash comes in, the cost of the 10% leaves its investment, and the difference is a gain of 30,000. |
|---|---|
| In the group accounts | Control is kept, so nothing is disposed of. It is a deal between the group’s owners and the new minority: the NCI takes on its share of Company F, and the difference to the proceeds goes to equity. The group shows no gain. |
2Choose the accounts
- Open Ownership & Equity → Ownership, and open Posting accounts with the gear beside Group structure.
- Choose an equity account for Equity transaction reserve.
- Choose the profit and loss account Your Group records its gain on selling shares in for Parent's gain/loss on sale of shares (P&L), and click Save.
Record the sale in Your Group’s own books with the gain on that same account: debit the bank 150,000, credit the investment in Company F 120,000, and credit the gain 30,000. BrizoConsol reads that account to check the gain (step 5).
3Record the sale
- Beside Company F’s Share purchases and sales, click + Record, then Sold shares.
- Keep Your Group (top organisation) as the parent, and choose Dec-2026 and 10.
- Keep the relationship as Subsidiary. This is what tells BrizoConsol control is kept.
- Enter the Disposal amount, 150,000, and click Add Record.
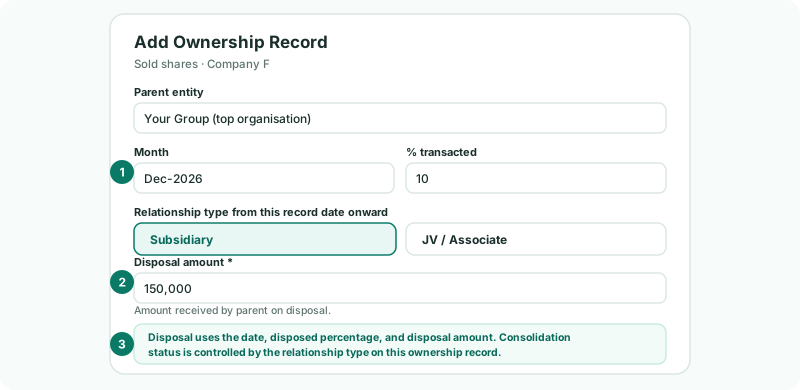
If you choose JV / Associate, the dialog asks for the retained interest instead: that is a sale that loses control, covered in Lose control and keep a stake.
Check
The new record reads Sold 10%, control kept and 80% → 70%, and Company F’s NCI % on the Ownership page is now 30%.
4Read how each figure is worked out
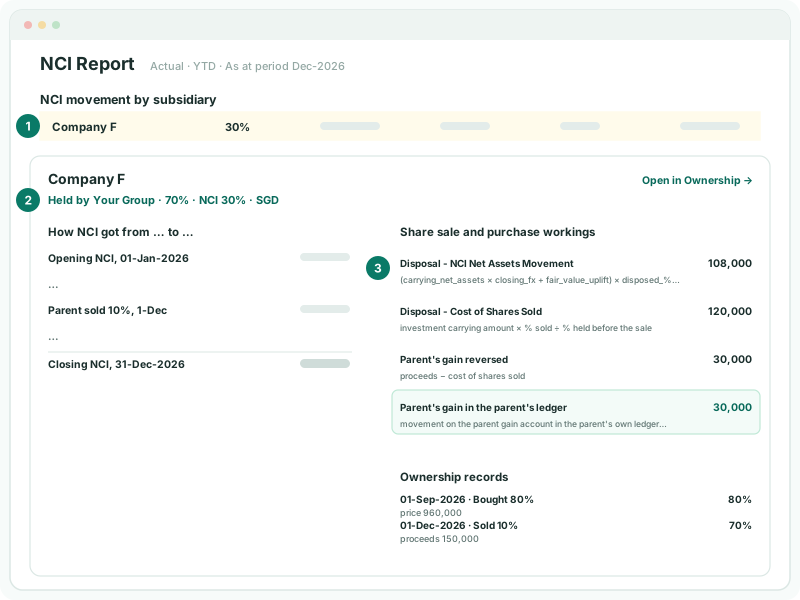
Saving the record recalculates the NCI and posts the entries. Open Ownership & Equity → NCI Report, choose Dec-2026, and click Company F’s row.
| Row | Formula | Amount |
|---|---|---|
| Disposal - NCI Net Assets Movement | (carrying_net_assets × closing_fx + fair_value_uplift) × disposed_% − cta_re_attributed | (1,000,000 + 80,000) × 10% = 108,000 |
| Disposal - Cost of Shares Sold | investment carrying amount × % sold ÷ % held before the sale | 960,000 × 10% ÷ 80% = 120,000 |
| Parent's gain reversed | proceeds − cost of shares sold | 150,000 − 120,000 = 30,000 |
| Parent's gain in the parent's ledger | movement on the parent gain account in the parent's own ledger for the month | 30,000 |
| The NCI’s share | The new minority takes 10% of Company F as the group carries it: its own equity at the closing rate, plus what is left of the fair-value uplift from the acquisition. Not the price they paid. |
|---|---|
| The cost of the shares sold | The share of Your Group’s total investment cost in Company F for the 10% sold. It is what Your Group took off its investment, so BrizoConsol puts it back before the investment is eliminated as before. |
| The parent’s gain | Proceeds less the cost of the shares sold. It is income in Your Group’s books, but not in the group’s, so BrizoConsol takes it back out. |
5Read the entry
| Account | Debit | Credit |
|---|---|---|
| Investment in subsidiary - Company F | 120,000 | |
| Parent's gain/loss on sale of shares | 30,000 | |
| Equity transaction reserve: the parent’s gain | 30,000 | |
| NCI - net assets | 108,000 | |
| Equity transaction reserve: the rest | 12,000 | |
| Total | 150,000 | 150,000 |
Together the reserve takes 42,000: the proceeds of 150,000 less the 108,000 the NCI takes on. Open Review → Elim. & Journals Report for Dec-2026, search for NCI-AUTO-ACQ, and open Auto NCI disposal posting Company F (DISPOSE). Its lines are Auto NCI cost of shares sold, Auto NCI parent gain on sale - disposal, Auto NCI parent gain moved to equity - disposal, Auto NCI net assets movement - disposal and Auto NCI equity transaction reserve - disposal.
If the gain in Your Group’s ledger for the month isn’t 30,000, the report adds Warning - parent gain does not agree with the ledger with the difference. That difference is left in group profit: correct the entry in Your Group’s books.
Check
On Reports → Profit & Loss for Dec-2026, the gain on sale of shares nets to nil for the group. On Reports → Balance Sheet, goodwill for Company F is still 160,000 and the equity transaction reserve shows 42,000.
6If Company F reports in another currency
Company F’s equity is translated at December’s closing rate, and 10% of its translation reserve moves from the owners’ CTA reserve to the new minority: Auto NCI CTA re-attribution - disposal credits NCI - share of CTA, and Auto NCI CTA re-attribution - disposal (owners) debits the CTA reserve. The full example is in Buy, sell or change your stake in a foreign company.
7If something goes wrong
| What you see | What to do |
|---|---|
| Select the account the parent posts its gain or loss on the sale of shares to, in Posting accounts on the Ownership page. | Choose Parent's gain/loss on sale of shares (P&L) in Posting accounts. |
| NCI other reserves account must be configured as equity transaction reserve for subsequent acquisition/disposal postings. | Choose Equity transaction reserve or NCI - share of other reserves in Posting accounts. |
| Disposal proceeds are required. | Enter the Disposal amount on the Sold record. |
| Missing closing exchange rate for Company F (… -> …) as of …. Add FX rates before posting the disposal. | Add the closing rate for Company F’s currency for the month of the sale. |
| Warning - parent gain does not agree with the ledger | Your Group’s gain for the month on the parent gain account differs from proceeds less the cost of the shares sold. Check the entry in Your Group’s books. |
| The dialog asks for the retained interest | The relationship is set to JV / Associate. Set it back to Subsidiary if the group keeps control. |
Want more detail? See the documentation