
Intercompany Eliminations · Track 5 · Tutorial 3 of 9
Eliminate loans and interest
A loan between group companies is an asset for the lender and a liability for the borrower, and the interest on it is income for one and an expense for the other. All four come out, and in a cross-currency loan the two sides move apart every month.
1Know what to eliminate
In October Company A lends Company C SGD 85,600, recorded by Company C as GBP 50,000. Company C pays interest of GBP 250 a month, and Company A records SGD 430.
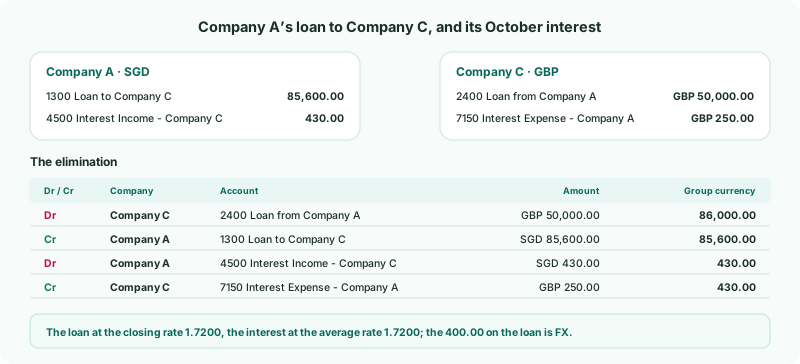
| The loan | A balance, translated at the closing rate. Company C’s GBP 50,000 is SGD 86,000 at 1.7200, against Company A’s SGD 85,600, so the sides differ by 400.00. That is an exchange difference: FX. |
|---|---|
| The interest | Income and expense for the month, translated at the average rate. |
| Accrued interest | Interest charged but not yet paid sits in a receivable and a payable. Eliminate those under Intercompany Loans too. |
2Choose how to clear it
| Use | When | See |
|---|---|---|
| A rule on Method 4 | You want to see and approve the loan’s elimination every month before it posts | Method 4: review and approve every month |
| A rule with several legs | The loan and the interest should be cleared by one rule | Build rules with several legs |
| A GL entry | A one-off loan, or an item no rule covers | Post a GL elimination entry |
A rule eliminates each month’s movement at that month’s rates, so it keeps up as the loan is drawn, repaid and retranslated. A GL entry stays in later months as it was posted: after the first month, enter only the change.
3Know what the type accepts
Under Intercompany → Intercompany Loans, an entry’s lines can use Current Asset, Non Current Asset, Current Liability, Non Current Liability, Interest Income and Interest Expense accounts. A loan booked to Accounts Receivable or Accounts Payable goes under Trade Receivables / Payables instead.
4Check the month
- Open the group’s Balance Sheet and Profit & Loss for October with Show Entities on.
Check
In the group column, the accounts 1300 and 2400 are mapped to are zero, and so are interest income and expense for Company C’s interest. The FX account holds the 400.00.
5If something goes wrong
| The loan is out by a different amount every month | That is the retranslation. With a GL entry, post each month’s change as FX, or clear the loan with a rule. |
|---|---|
| The FX difference is large | Check the rates on each line against the group’s closing and average rates for the month, and look for a drawdown or repayment one company hasn’t booked. |
| … cannot be used in this elimination type. | The account isn’t one Intercompany Loans accepts. Check its type in the company’s chart. |
Want more detail? See the documentation