
UK GAAP Groups · Track 3 · Tutorial 1 of 4
Read the balance sheet and profit and loss
Available on ProPremium
The UK GAAP balance sheet and profit and loss show the same consolidated figures as the Base Balance Sheet and Profit & Loss, laid out in the Companies Act formats FRS 102 uses: net assets above, capital and reserves below. Most lines come from account sections; a few come from the classifications you set.
1Know where the lines come from
| From the account sections | Fixed assets, current assets, creditors, turnover, cost of sales, interest and tax. Each line adds up the accounts in a section of the Common COA, such as Bank or Non-Current Liability. Nothing to classify. |
|---|---|
| From the account names | Intangible Assets: the goodwill accounts, recognised by their name or chosen on Goodwill on the Balance Sheet tab of the Accounting Standard page. |
| From your classifications | Every line of capital and reserves, Distribution Costs, Administrative Expenses and Share of Profit of Associates. Each reads the accounts you put on it on the Accounting Standard page. |
| Worked out | Subtotals, and the lines that are the rest of a section: Investments, Other Operating Income and Other Operating Expenses. |
The figures are the one consolidation, so the UK GAAP statements agree with the Base reports. Where they don’t, a classification is missing.
2Read the balance sheet
- Select Your Group, and open Reports → All Reports → Consolidated Balance Sheet.
- Choose the month. The statement shows the balances at the end of it.
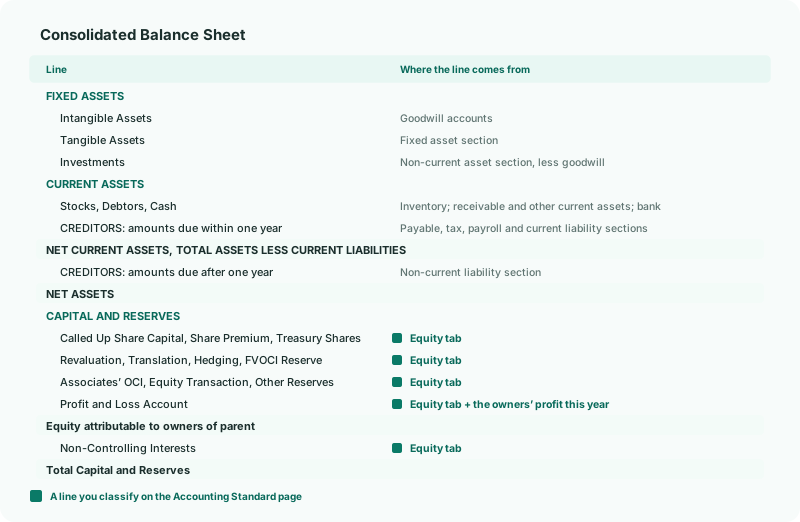
| Intangible Assets | Goodwill, from the accounts named as goodwill or chosen on Goodwill on the Balance Sheet tab — the goodwill account chosen in a subsidiary’s Totals and accounts for this company is one. |
|---|---|
| Tangible Assets | The fixed asset section, such as 1600 Plant & Equipment. |
| Investments | The rest of the non-current assets, including an investment in an associate. See Account for associates and joint ventures. |
| Debtors | Trade debtors and other current assets together. |
| CREDITORS: amounts due within one year, after one year | The current liability sections, and the non-current liability section. |
| NET ASSETS | Total assets less current liabilities, less creditors due after one year. |
| Profit and Loss Account | The accounts on the Profit and Loss Account line plus the year’s profit so far that belongs to the owners. The NCI’s share is in Non-Controlling Interests. |
| Reserves | Each from its line on the Equity tab: Revaluation Reserve, Translation Reserve, Hedging Reserve, FVOCI Reserve, Share of OCI of Associates, Equity Transaction Reserve and Other Reserves. |
| Non-Controlling Interests | The accounts on the Non-Controlling Interest line. Accounts created in Posting accounts are classified from their names, so NCI Net Assets, NCI Share of Profit, NCI Share of CTA and NCI Share of Other Reserves all land here. |
3Read the profit and loss
- Open Reports → All Reports → Consolidated Profit and Loss Account for 2026.
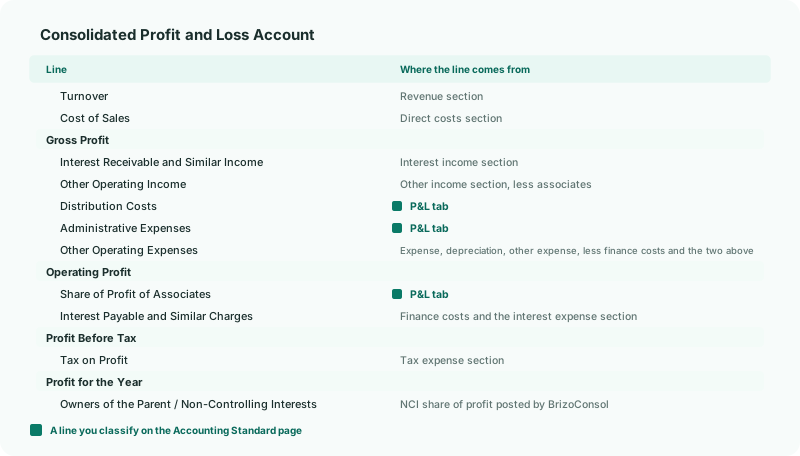
| Turnover, Cost of Sales | The UK names for revenue and cost of revenue. |
|---|---|
| Other Operating Expenses | The expense, depreciation and other expense sections, less finance costs, Distribution Costs and Administrative Expenses. For Your Group: Distribution Costs 310,000, Administrative Expenses 520,000, Operating Profit 1,304,000. |
| Interest Receivable and Similar Income | Shown above Operating Profit, but added after it: Operating Profit doesn’t include it. |
| Share of Profit of Associates | After Operating Profit, and taken out of Other Operating Income. |
| Interest Payable and Similar Charges | The finance costs and the interest expense section. |
| Owners of the Parent, Non-Controlling Interests | The NCI’s share is the share of profit BrizoConsol posts for each subsidiary with an NCI; the owners’ share is the rest. |
4Check against the Base reports
- Open the group’s Balance Sheet and Profit & Loss for the same month and year.
Check
On the UK GAAP balance sheet, NET ASSETS equals Total Capital and Reserves, and Total Capital and Reserves equals the Balance Sheet’s equity — 1,817,100 for Your Group. Profit for the Year on the UK GAAP profit and loss equals Net Profit on Profit & Loss.
5If something goes wrong
| Total Capital and Reserves is lower than NET ASSETS | An equity account isn’t classified. Put it on its line on the Equity tab — see Switch on UK GAAP and classify equity. |
| Other Operating Expenses is negative | An account on Distribution Costs or Administrative Expenses isn’t an expense. Take it off. |
| Intangible Assets is empty, but the group has goodwill | The goodwill account’s name wasn’t recognised, so it is in Investments. Choose it on Goodwill on the Balance Sheet tab of the Accounting Standard page, and click Save Changes. |
| The UK GAAP statements aren’t in All Reports | Select the group, not a company. UK GAAP must be enabled and saved for it. |
Want more detail? See the documentation