
Ownership and NCI · Track 3 · Tutorial 4 of 4
Pay dividends to the NCI
When a subsidiary that isn’t wholly owned pays a dividend, part goes to the parent and part to the minority shareholders. The parent’s part is intercompany, so you eliminate it. The minority’s part is a real payment out of the group, and it reduces the NCI. BrizoConsol makes that reduction for you, from the subsidiary’s own equity.
1Know how the dividend splits
In December 2026, Company B, 80% owned by Your Group, declares and pays a dividend of AUD 50,000. It records it in its own books in 3300 Dividends Paid, an equity account.
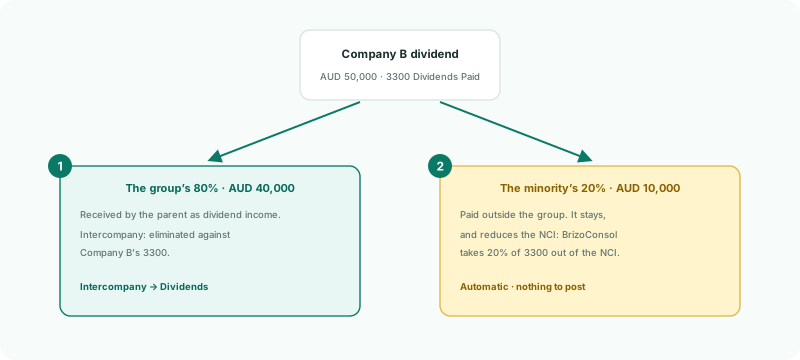
| The group’s 80% | AUD 40,000, received by the parent and recorded as dividend income. Inside the group, it is cash moving from one company to another: eliminate it. |
|---|---|
| The minority’s 20% | AUD 10,000, paid to shareholders outside the group. It isn’t intercompany, so it stays. It is the NCI being paid out, so it reduces the NCI, not the owners’ equity. |
2Eliminate the group’s share
- Open Intercompany → Dividends, choose Dec-2026, and add an elimination entry.
- Debit the parent’s dividend income with its amount in SGD, and credit Company B’s 3300 Dividends Paid with AUD 40,000, at the same rate.
Eliminate 80% only. The full steps are in Eliminate intercompany dividends.
3Let BrizoConsol reduce the NCI
There is nothing to post for the minority’s share. The NCI’s share of net assets is worked out from Company B’s closing equity — every equity account except the year’s profit — at its NCI %, at the closing rate. 3300 Dividends Paid is one of those accounts, so the dividend lowers Company B’s equity by AUD 50,000 and the NCI’s share of it by AUD 10,000.
The entry is part of Company B’s NCI net assets posting, on the line Auto NCI net assets source equity - Company B for 3300: a debit to NCI - net assets and a credit to the group account 3300 is mapped to, for AUD 10,000 at December’s closing rate.
| In the group accounts | AUD |
|---|---|
| Company B’s dividend, in 3300 | 50,000 |
| Less the group’s share, eliminated | (40,000) |
| Less the minority’s share, moved to the NCI | (10,000) |
| Left in the owners’ equity | 0 |
A dividend declared but not yet paid works the same way, from the month it is recorded in equity. The amount owed to the minority shareholders stays in the group balance sheet as a liability until it is paid, because it is owed outside the group.
4Check the month
- Open Ownership & Equity → NCI Report for Company B, YTD, Dec-2026, and find the NCI Net Assets row for 3300. Its formula is equity_closing_balance × NCI% × closing_fx and its NCI % is 20.00%.
- Open Reports → Balance Sheet for Dec-2026 with Show Entities on.
Check
On the NCI Report, the 3300 row’s base is Company B’s (50,000), if it paid no other dividend this year, and its amount is 20% of it, AUD (10,000), at December’s closing rate. On the balance sheet, Dividends Paid is zero in the group column, and on the group profit and loss the parent’s dividend income from Company B is zero.
5Post a dividend adjustment by hand
If the automatic share doesn’t cover a dividend correctly — for example a dividend on a class of shares the NCI % doesn’t describe, or a correction agreed with the auditors — post the adjustment as a journal:
- Open Adjustments → Consolidation Journals, and click + Add a new journal entry.
- Choose Dividend to NCI as its type, enter the lines, and save it.
Journals of this type are listed as Dividend NCI, are counted on Month End Status as Dividend NCI journals, and show with the NCI entries on the reports. Don’t post an ordinary dividend this way as well: the minority’s share is already taken out by step 3, so a journal for it too would count it twice.
6If something goes wrong
| What you see | What to do |
|---|---|
| The whole dividend disappears, and the NCI doesn’t fall | The elimination took 100%. Eliminate only the parent’s 80%. |
| The NCI’s share of profit falls instead of its net assets | Company B recorded the dividend in a profit and loss account. It belongs in equity; correct it in Company B’s books or its mapping. |
| The NCI falls by twice the minority’s share | A Dividend to NCI journal repeats the automatic reduction. Delete the journal. |
| The dividend shows in the wrong month | Company B recorded it in another month. The NCI follows Company B’s own books. |
Want more detail? See the documentation