
Intercompany Eliminations · Track 5 · Tutorial 5 of 9
Eliminate intercompany dividends
When a subsidiary pays a dividend, the parent records income and the subsidiary records a distribution out of its equity. For the group, the part paid to the parent is cash moving between its own companies: it comes out. The part paid to minority shareholders stays.
1Know what to eliminate
In December 2026 Company B, 80% owned by Your Group through Company A, declares and pays a dividend of AUD 50,000, recorded in 3300 Dividends Paid. Company A receives AUD 40,000 and records SGD 35,840.00 in 4200 Dividend Income.
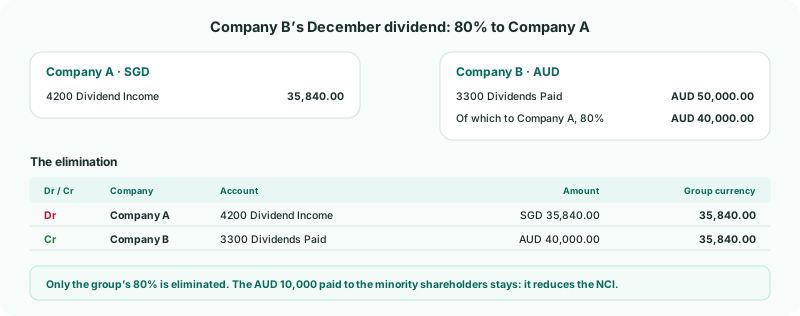
| The group’s 80% | Company A’s dividend income against AUD 40,000 of Company B’s distribution. Both come out. |
|---|---|
| The minority’s 20% | AUD 10,000 paid to shareholders outside the group. It isn’t intercompany, so it stays: it reduces Non-Controlling Interests and shows as a dividend to them. |
2Enter the elimination
- Open Intercompany → Dividends, choose Dec-2026, and click + Add entry.
- Debit Company A’s 4200 Dividend Income, SGD 35,840.00 at 1.0000.
- Credit Company B’s 3300 Dividends Paid, AUD 40,000.00 at 0.8960, and click Confirm.
A dividend is usually a one-off, so a GL entry suits it — see Post a GL elimination entry. Date it in the month the dividend is recorded. Use the same rate on both sides, so the entry balances; a difference between them is an exchange difference.
3Know what the type accepts
Under Intercompany → Dividends, an entry’s lines can use Equity, Other Income, Accounts Receivable and Accounts Payable accounts. A dividend declared but not yet paid leaves a receivable and a payable: eliminate them in the same entry if they are in Accounts Receivable and Accounts Payable, or under Trade Receivables / Payables if the payable is in Current Liabilities.
4Check the month
- Open the group’s Profit & Loss and Balance Sheet for December with Show Entities on.
Check
Dividend income is zero in the group column. Of Company B’s distribution, only the AUD 10,000 paid to the minority shareholders is left.
5If something goes wrong
| The whole dividend disappears | The entry eliminated 100%. Eliminate only the parent’s share of the distribution. |
|---|---|
| The dividend income is still in the group figures | The parent booked it to an account the entry didn’t use, or in a different month. Check Company A’s books. |
| … cannot be used in this elimination type. | The account isn’t Equity, Other Income, Accounts Receivable or Accounts Payable. Check its type in the company’s chart. |
Want more detail? See the documentation