
Ownership and NCI · Track 2 · Tutorial 2 of 4
Recognise a gain on a bargain purchase
Now and then a group buys a company for less than its net assets are worth: a forced sale, a seller in difficulty. Goodwill would be negative, so there is none; the difference is a gain in profit and loss in the month of the purchase. BrizoConsol works it out from the same three figures it uses for goodwill.
1Know when there is a gain
In October 2026, Your Group buys 80% of Company H from a seller who needed a quick sale. It pays 700,000. The purchase price allocation values Company H’s identifiable net assets at 1,000,000, and the NCI is measured at its share of them, 200,000.
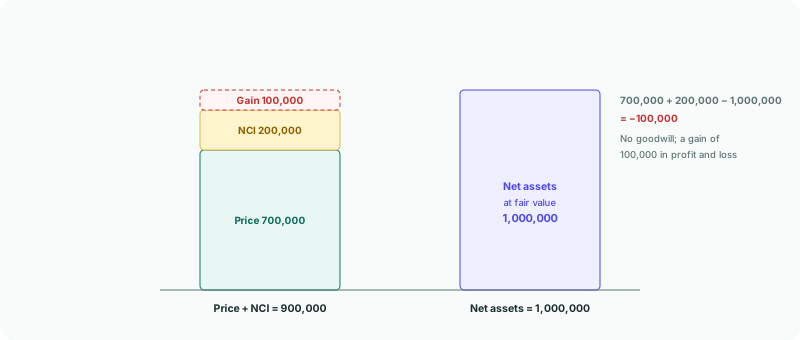
Goodwill is the price plus the NCI less the net assets: 700,000 + 200,000 − 1,000,000 = −100,000. A negative result is not negative goodwill. It is a gain of 100,000, recognised in profit and loss when the group takes control.
2Check the figures before you record them
A gain on a purchase is unusual, so most standards expect you to check, before you recognise it, that every asset and liability has been identified and that each figure is measured correctly. Go back over:
| The net assets | Every asset and liability valued, including liabilities the seller hadn’t recorded, such as provisions and contingent liabilities. |
|---|---|
| The price | Everything the group gave, including deferred and contingent amounts at their fair value. |
| The NCI | At its share of the net assets, or its fair value if that is how you measure it. |
If the gain is still there after that review, record it. Under UK GAAP, FRS 102 treats the excess differently from IFRS; check what your standard requires before you report it.
3Record the purchase
- Open Ownership & Equity → Ownership, and click Company H.
- Beside Share purchases and sales, click + Record, then Bought shares, and choose Your Group, Oct-2026, 80 and Subsidiary.
- Enter the Investment cost (group currency), 700,000, and the Net assets at date (fair value), 1,000,000.
- Keep Share of net assets (partial goodwill), and click Add Record.
- Under Totals and accounts for this company, choose Investment in subsidiary - Company H, and click Save.
- If the record shows Needs Gain on bargain purchase, click Choose, choose the account in Posting accounts, and click Save.
There is no goodwill, so Goodwill - Company H isn’t needed and Company H isn’t held up without it. The gain goes to the group’s Gain on bargain purchase posting account.
4Read the gain where it is shown
| Where | What it shows |
|---|---|
| Share purchases and sales | The record shows Gain on bargain purchase 100,000.00 in place of goodwill. |
| Totals and accounts for this company | Acquisition goodwill is 0.00, and Bargain purchase gain is 100,000, with the note that it is the same formula where negative, recognised in profit or loss. |
| NCI Report, Company H, Oct-2026 | Under How each figure was worked out, a Gain on Bargain Purchase row, formula balancing amount, 100,000, posted to the gain account, in place of the Goodwill row. Under Ownership records, the record’s goodwill shows the negative figure. |
The rest of the entry is the same as any acquisition: Company H’s equity and pre-acquisition profit eliminated, the fair value adjustment, the investment, and the NCI of 200,000. See Read the acquisition entries line by line.
5Check the profit and loss
- Open Reports → Profit & Loss for Oct-2026.
- Click the amount on the line the gain account is reported in, to drill into it.
Check
The gain account shows 100,000 in October, posted by the line Auto NCI gain on bargain purchase, and nothing in September. The group’s profit for October includes it in full: it belongs to the owners of the parent, because it arose on the group’s purchase.
6Change the figures after the review
If the purchase price allocation is revised — a liability found, a valuation corrected — edit the record with the new figures and click Save Changes. The gain is worked out again. If the figures now make goodwill, the gain disappears and Company H needs a Goodwill - Company H account before it posts again.
7If something goes wrong
| What you see | What to do |
|---|---|
| Gain on bargain purchase account must be configured for acquisition posting with negative goodwill. | Choose the Gain on bargain purchase account in Posting accounts, and click Save. |
| A gain you didn’t expect | Check the price includes everything the group gave, and that the price and the net assets are both in the group currency. |
| Goodwill account must be configured… after a revision | The revised figures make goodwill. Choose Goodwill - Company H under Totals and accounts for this company. |
Want more detail? See the documentation