
Intercompany Eliminations · Track 5 · Tutorial 8 of 9
Make rental and lease adjustments
When one group company lets property or equipment to another, the group has neither a lease nor rental income. What the lessee recorded depends on its standard, so the elimination is worked out from the lease schedule, not from invoices alone.
1Know what the lessee recorded
Company A lets office space to Company B for SGD 5,000 a month. Company A records rental income. What Company B records depends on its standard:
| Company B records | Eliminate |
|---|---|
| Rent expense — a short-term lease, or a local standard that expenses rent | Company A’s rental income against Company B’s rent expense. |
| A right-of-use asset and lease liability, with depreciation and interest — IFRS 16 or a standard like it | Company A’s rental income against Company B’s depreciation and interest for the month, and Company B’s right-of-use asset against its lease liability, from the lease schedule. |
2Eliminate rent against rent
Company B expenses the rent: AUD 5,580.36 in October, SGD 5,000.00 at 0.8960.
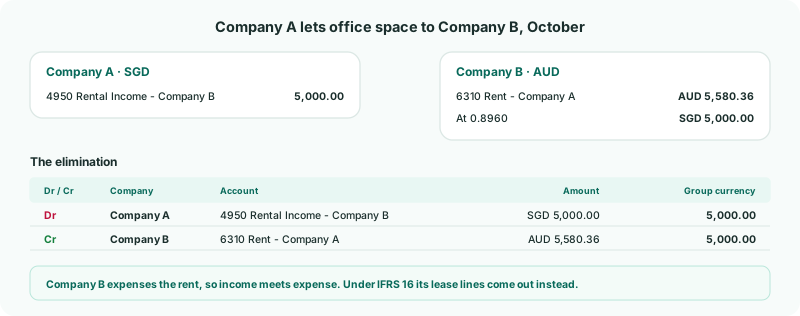
- Open Intercompany → Rental / Lease Adjustments, choose Oct-2026, and click + Add entry.
- Debit Company A’s 4950 Rental Income - Company B, SGD 5,000.00. Credit Company B’s 6310 Rent - Company A, AUD 5,580.36 at 0.8960. Click Confirm.
Rent that is the same every month on accounts that hold nothing else can be cleared by a rule instead — see the Automate with rules track.
3Eliminate a lease the lessee recognised
When Company B applies IFRS 16, the entry takes several lines, all from its lease schedule for the month: debit Company A’s rental income, credit Company B’s depreciation and interest expense; and, for the balances, debit Company B’s lease liability and credit its right-of-use asset and accumulated depreciation. Click + Add line for each.
Rental income and the depreciation and interest rarely agree month by month. Treat the difference with a justification that points to the schedule — see Allocate a difference on a manual entry. The asset and liability lines stay in later months as they were posted, so after the first month enter only their change.
Don’t post a group lease journal, as in the IFRS series, for a lease between group companies: the group has no lease to recognise.
4Know what the type accepts
Under Rental / Lease Adjustments, an entry’s lines can use Revenue, Other Income, Expense, Other Expense, Direct Costs, Fixed Asset, Non Current Asset, Non Current Liability, Current Liability, Depreciation, Interest Income and Interest Expense accounts.
Check
On the group’s Profit & Loss for October with Show Entities on, rental income from Company B and Company B’s rent are zero in the group column.
5If something goes wrong
| Rental / Lease Adjustments isn’t in the Intercompany menu | It is off in a new group. Switch it on, as in Switch on and add intercompany types. |
|---|---|
| The right-of-use asset is still in the group figures | The balance lines weren’t in the entry. Add them from the lease schedule. |
| … cannot be used in this elimination type. | The account isn’t one the type accepts, such as an Accounts Payable account. Eliminate the unpaid rent under Trade Receivables / Payables. |
Want more detail? See the documentation