
Intercompany Eliminations · Track 5 · Tutorial 7 of 9
Eliminate fixed asset transfers
When one group company sells an asset to another for more than its carrying amount, the seller records a gain and the buyer records the asset at the higher price. For the group, nothing was sold: the gain comes out of the asset, and so does the extra depreciation the buyer charges on it.
1Know what to eliminate
On 1 October 2026 Company A sells equipment to Company B for SGD 60,000. It was in Company A’s books at SGD 48,000, so Company A records a gain of SGD 12,000 in 4960 Gain on Disposal of Assets. Company B records AUD 66,964.29 in 1600 Equipment and depreciates it over five years: AUD 1,116.07 a month, SGD 1,000.00 at 0.8960.
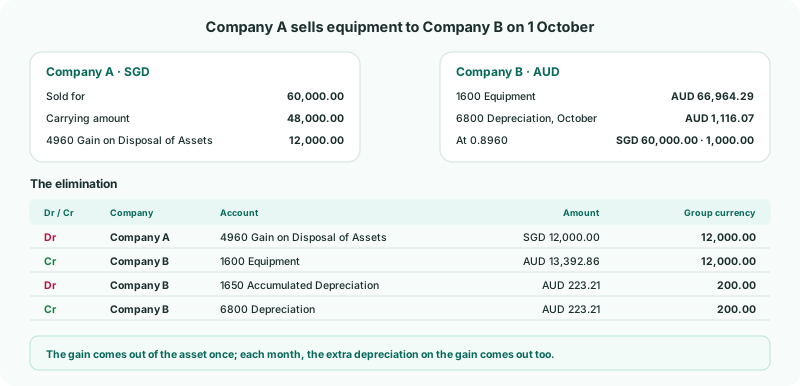
| The gain | SGD 12,000 out of Company A’s gain and out of Company B’s equipment, so the group keeps the asset at its original SGD 48,000. |
|---|---|
| The extra depreciation | Company B depreciates SGD 60,000; the group depreciates SGD 48,000. The difference, 12,000 ÷ 60 = SGD 200 a month, comes out of depreciation and out of accumulated depreciation. |
2Enter October’s entry
- Open Intercompany → Fixed Assets, choose Oct-2026, and click + Add entry.
- Enter the Elimination ID FA-A-B-2026-10, and the Description Equipment sold by Company A to Company B, October 2026.
- Debit Company A’s 4960 Gain on Disposal of Assets, SGD 12,000.00. Credit Company B’s 1600 Equipment, AUD 13,392.86 at 0.8960.
- Click + Add line on each side. Debit Company B’s 1650 Accumulated Depreciation, AUD 223.21 at 0.8960. Credit Company B’s 6800 Depreciation, AUD 223.21 at 0.8960.
- Click Confirm.
Under Fixed Assets, an entry’s lines can use Fixed Asset, Depreciation, Revenue, Other Income and Other Expense accounts. A loss on the transfer is eliminated the other way round: debit the asset, credit the loss.
3Enter later months
The equipment and accumulated depreciation lines stay in later months as they were posted. Income and costs count for the month they are in. So each later month:
- Add an entry under that month with only the depreciation lines: debit Company B’s 1650 Accumulated Depreciation, credit its 6800 Depreciation, AUD 223.21 each.
Accumulated depreciation then builds up SGD 200 a month, until the gain is fully depreciated or the asset leaves the group. If Company B sells the asset outside the group, the gain still in its cost is the group’s profit: take the asset and accumulated depreciation lines out against Company B’s gain or loss on that sale.
Check
On the group’s Balance Sheet for October with Show Entities on, the equipment in the group column is SGD 12,000.00 lower than the companies’ total. On the Profit & Loss, Company A’s gain is gone and depreciation is SGD 200.00 lower.
4If something goes wrong
| Fixed Assets isn’t in the Intercompany menu | It is off in a new group. Switch it on, as in Switch on and add intercompany types. |
|---|---|
| The equipment is reduced twice | The gain lines were entered again in a later month. They stay as posted: later months need only the depreciation lines. |
| … cannot be used in this elimination type. | The account isn’t one the type accepts, such as an Accounts Receivable account for the unpaid price. Eliminate that under Trade Receivables / Payables. |
Want more detail? See the documentation