
Hospitality Groups · Track 2 · Tutorial 1 of 2
Eliminate PropCo/OpCo leases, including variable rent
A hotel OpCo that leases its hotel from a PropCo in the same group records a lease the group doesn’t have. Its variable rent is in no lease balance, so it is the part most often left behind, and the group figures keep income and expense that should be gone.
1Know what each company records
Hotel OpCo leases its hotel from PropCo, a company in the same group. The rent has two parts: a fixed 100,000 a month, and a variable rent of 4% of room revenue, 18,000 in October 2026. Under IFRS 16 the two companies record it differently:
| PropCo, the lessor | Hotel OpCo, the lessee | |
|---|---|---|
| Fixed rent | Rental income each month | A right-of-use asset and a lease liability, then depreciation and interest each month |
| Variable rent | Rental income each month | An expense each month. Rent that depends on sales is left out of the lease liability (IFRS 16.27 and 16.38(b)), so it is on no balance sheet. |
For the group there is no lease: the hotel is the group’s own property. So all of it comes out — PropCo’s fixed and variable rental income, the OpCo’s depreciation, interest and variable rent, and the OpCo’s right-of-use asset and lease liability. Leave out the variable rent, and income and expense of 18,000 a month stay in the group figures.
2Take the figures from the lease schedule
From the OpCo’s lease schedule and ledger, note for October:
| Item | October | Where it is |
|---|---|---|
| Fixed rental income | 100,000.00 | PropCo, 4900 Rental Income - Hotel OpCo |
| Variable rent | 18,000.00 | PropCo, 4910 Variable Rent Income - Hotel OpCo; Hotel OpCo, 6320 Variable Rent - PropCo |
| Depreciation of the right-of-use asset | 70,000.00 | Hotel OpCo, 6800, and its accumulated depreciation 1660 |
| Interest on the lease liability | 24,600.00 | Hotel OpCo, 7100 Lease Interest - PropCo |
| Fall in the lease liability: 100,000 paid less 24,600 interest | 75,400.00 | Hotel OpCo, 2650 Lease Liability - PropCo |
The account codes are an example: use the dedicated intercompany accounts in your companies’ charts.
3Enter the month’s entry
- Select Your Group, open Intercompany → Rental / Lease Adjustments, choose Oct-2026, and click Add a new Elimination Entry.
- Enter an Elimination ID, such as LEASE-OCT26, and a Description that names the lease and the schedule.
- Under Debit Lines, add PropCo’s 4900 for 100,000.00 and 4910 for 18,000.00, and the OpCo’s 1660 for 70,000.00. Click Add line for each line after the first.
- Under Credit Lines, add the OpCo’s 6800 for 70,000.00, 7100 for 24,600.00, 2650 for 75,400.00 and 6320 for 18,000.00.
- Debits and credits are both 188,000.00, so there is no difference to allocate. Click Confirm.
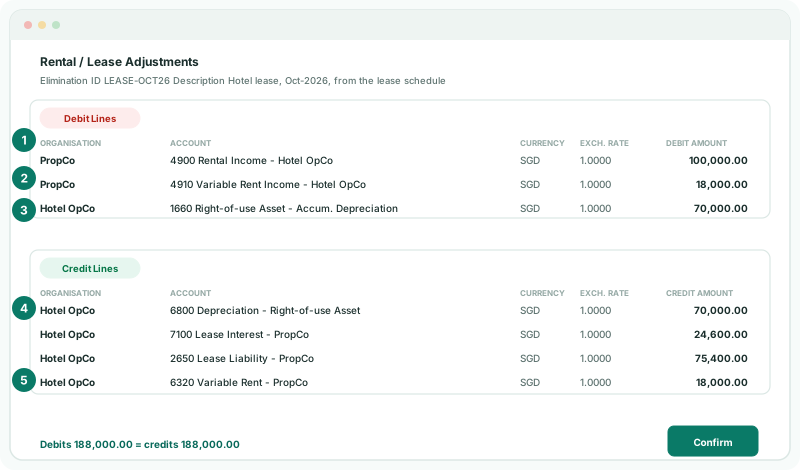
An entry stays in later months as it was posted, so each month enter that month’s income and costs and only the change in the asset and liability, as here. In the month the lease starts, eliminate the whole right-of-use asset and lease liability instead of their change. With every line in, the entry balances: what PropCo earned less what the OpCo expensed is exactly the gap between the OpCo’s asset and liability.
If the variable rent sits on accounts that hold nothing else, a rule can clear those two lines instead — see the Automate with rules track — and the monthly entry keeps the fixed lease only.
4Treat the hotel as the group’s own property
If PropCo carries the hotel as investment property, the group doesn’t: a property let to another group company and used by it is owner-occupied in the consolidated accounts (IAS 40.15), and is carried as property, plant and equipment. BrizoConsol has no feature for this reclassification: post it with a journal under Adjustments → Consolidation Journals, as in Post group adjustments.
Check
On the group’s Profit & Loss for Oct-2026 with Show Entities on, the group column shows zero for PropCo’s rental and variable rent income and for the OpCo’s depreciation, interest and variable rent on this lease. On the Balance Sheet, the OpCo’s right-of-use asset and lease liability for the hotel are zero in the group column.
5If something goes wrong
| Income and expense of the same amount are left in the group figures | The variable rent isn’t in the entry or a rule. Add its two lines. |
|---|---|
| The entry doesn’t balance | A line is missing or is for the wrong month. Check each line against the lease schedule: with every line in, there is no difference. Don’t allocate a difference that comes from a missing line. |
| The right-of-use asset or lease liability is still in the group figures | The entry in the month the lease started didn’t eliminate the whole balances. Add the rest. |
| … cannot be used in this elimination type. | The account isn’t one Rental / Lease Adjustments accepts, such as an Accounts Payable account. Clear unpaid rent under Trade Receivables / Payables. |
Want more detail? See the documentation