
Construction Groups · Track 3 · Tutorial 2 of 2
Recognise an onerous contract at group level
When a fixed-price contract turns loss-making, IAS 37 requires the whole expected loss on the remaining work to be provided now, not as the work is done. If a subsidiary’s books don’t provide for it, the group does, with a journal it updates every month.
1Know when the group recognises it
A contract is onerous when the unavoidable costs of meeting it exceed the benefits still to come from it. IAS 37 requires a provision for the excess as soon as that is so. The cost of fulfilling a contract includes the costs that relate directly to it: the extra costs of doing the work, and a share of other costs that relate directly to contracts.
Company A’s books may already provide for it. Recognise it at group level when they don’t:
| Situation | At group level |
|---|---|
| Company A’s books provide for the loss | Nothing more. The provision comes in with its figures. |
| Company A’s own standard or its own review doesn’t pick it up | A GAAP journal for the provision. |
| The contract is loss-making only once the group’s own costs are counted, for example because work is subcontracted to a group company at a price below that company’s cost | A GAAP journal, measured on the group’s total remaining costs, not on the subcontract price. |
Before providing, write down any assets dedicated to the contract that are impaired, such as costs to fulfil it held as an asset.
2Work out the provision
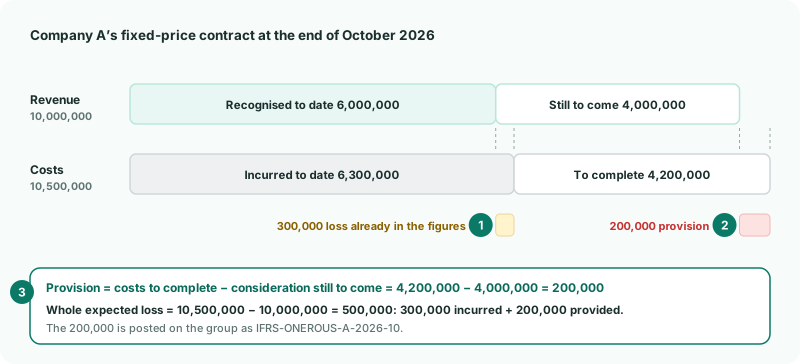
Company A has a fixed-price contract for 10,000,000. At the end of October 2026, the review gives:
| Revenue recognised to date | 6,000,000 |
|---|---|
| Costs incurred to date | 6,300,000: a loss of 300,000 already in the figures |
| Consideration still to come | 4,000,000 |
| Costs to complete | 4,200,000 |
| Provision | 4,200,000 − 4,000,000 = 200,000 |
The whole expected loss on the contract, 500,000, is then in the group figures: 300,000 incurred and 200,000 provided.
3Post the provision
- Select Your Group, open Adjustments → GAAP Journals, and choose Oct-2026.
- Click + Add a new journal entry.
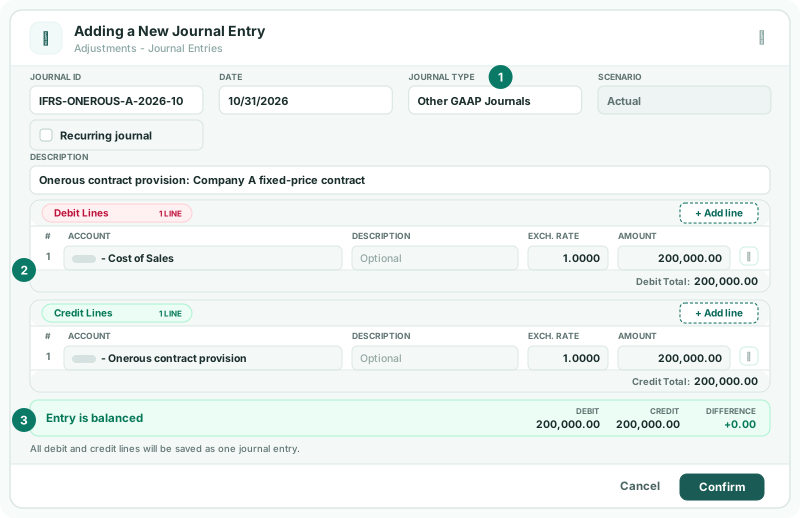
- Enter the Journal ID IFRS-ONEROUS-A-2026-10, the date 31 October 2026, the Journal Type Other GAAP Journals, and a Description that names the contract.
- Debit Cost of Sales 200,000, credit your onerous contract provision account 200,000, and click Confirm when Entry is balanced shows.
There is no journal type for provisions, so use Other GAAP Journals and keep the ONEROUS in the Journal ID. GAAP Journals is in the menu once IFRS is enabled for the group; see Switch on IFRS and classify equity.
4Update it every month
Each month, review the costs to complete again, and post the change in the provision.
| In November | Journal |
|---|---|
| Work billed 1,000,000 at a cost of 1,050,000; estimates unchanged. The provision needed falls to 150,000. | IFRS-ONEROUS-A-2026-11: Dr provision 50,000 / Cr Cost of Sales 50,000, so the 50,000 loss incurred is met from the provision. |
| Costs to complete rise by a further 80,000. | Dr Cost of Sales / Cr provision for the increase as well. |
When the contract is complete, the provision is nil.
5Check the provision
- On GAAP Journals, type ONEROUS in the search box.
- Open Reports → Balance Sheet for Oct-2026, and drill into the provision account.
Check
The provision account shows 200,000 for October, from IFRS-ONEROUS-A-2026-10 only. On Reports → Profit & Loss with Show Entities on, the 200,000 is in the group’s cost of sales and not in Company A’s column.
To place the provision on the IFRS balance sheet, classify its account as in Classify profit or loss and cash flow lines.
6If something goes wrong
| What you see | What to do |
|---|---|
| GAAP Journals isn’t under Adjustments | No accounting standard is enabled for the group. Enable IFRS on the Accounting Standard page. |
| Journal ID already exists: … | Each Journal ID can be used once. Add the month, as in IFRS-ONEROUS-A-2026-11. |
| Debit and Credit totals must be balanced before saving. | Check the amounts until the entry is balanced. |
| One or more selected periods are locked. | The month is locked. Ask an administrator to unlock it, or post in an open month. |
| The loss is counted twice | Company A has also provided for it in its own books. Delete the group journal. |
Want more detail? See the documentation