
IFRS Groups · Track 1 · Tutorial 2 of 2
Classify profit or loss and cash flow lines
Available on ProPremium
The IFRS profit or loss shows distribution costs and administrative expenses on their own lines, and the IFRS cash flow statement shows each investing and financing flow. Both read those lines from the accounts you classify.
1Know how the lines are filled
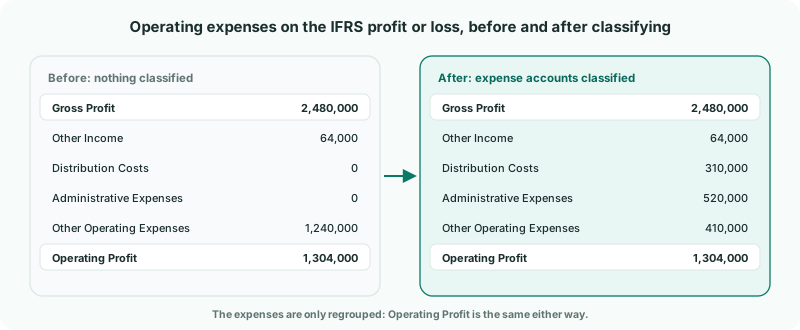
| Profit or loss | Distribution Costs and Administrative Expenses are the accounts you classify. Other Operating Expenses is everything else in the expense, depreciation and other expense sections, apart from finance costs. Classifying only moves expenses between these three lines: operating profit doesn’t change. |
|---|---|
| Cash flow | Each investing and financing line is the year’s movement on the accounts you classify. The operating section is worked out from profit, depreciation and working capital, and needs no classification apart from Gain/Loss on Disposal. |
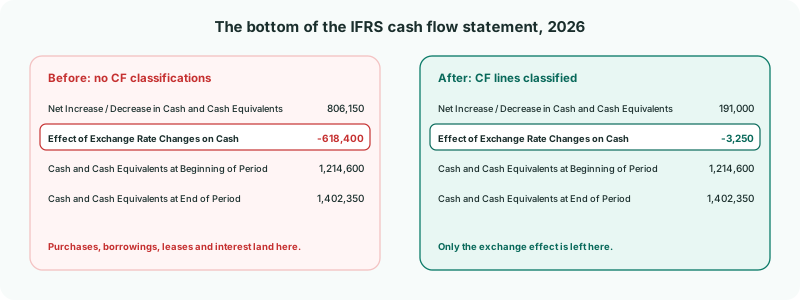
| What isn’t classified | The statement still ends at the bank balance. A movement that isn’t on any line shows in Effect of Exchange Rate Changes on Cash, which is the difference between the cash movement and the three sections. |
2Classify the profit or loss lines
- Select Your Group, and open Settings → Organisation Settings → Accounting Standard.
- Under Account Classifications, choose P&L in the Type column.
- On Distribution Costs, click Select accounts. In Select P&L Accounts, tick 6100 Selling & Marketing and 6150 Delivery Costs, and click Apply.
- On Administrative Expenses, select 6300 Office Rent, 6400 Admin Salaries and 6500 Professional Fees.
| Which accounts | Expense accounts only. Other Operating Expenses is the expense, depreciation and other expense sections, less finance costs and these two lines, so a cost-of-sales account classified here would also stay in Cost of Revenue and show twice. |
|---|---|
| Share of Profit of Associates | The account your share of an associate’s profit is posted to, from the Other Income section. Your Group has no associate yet; this line is set in Account for associates and joint ventures. |
3Classify the cash flow lines
- Choose CF in the Type column. The lines are grouped into Operating, Investing and Financing activities.
- On each line your group uses, click Select accounts, tick the account in Select Cash Flow Accounts, and click Apply.
- Click Save Changes.
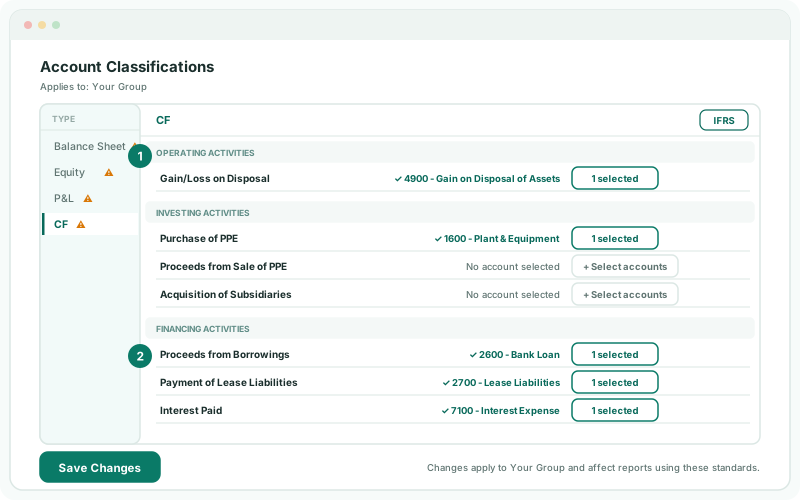
Choose the account whose movement over the year is that cash flow:
| Line | Your Group’s account |
|---|---|
| Gain/Loss on Disposal | 4900 Gain on Disposal of Assets. The gain is taken out of operating cash flow because it isn’t cash. |
| Purchase of PPE | 1600 Plant & Equipment, the cost account. Its increase is the year’s purchases when nothing was sold. |
| Proceeds from Borrowings | 2600 Bank Loan. |
| Payment of Lease Liabilities | 2700 Lease Liabilities. |
| Interest Paid | 7100 Interest Expense. IFRS allows interest paid in operating or financing activities; the IFRS statement shows it under financing, and adds finance costs back in the operating section. |
A cash flow line is a second classification: an account can be on one Equity or P&L line and also on one CF line. So an equity account keeps its equity line and can be given the financing line its movement belongs to — for a share issue, 3000 Share Capital on Proceeds from Issue of Share Capital. Putting an account on two CF lines, or on two Equity or P&L lines, gives The same account cannot be used for multiple classifications within the same standard. when you save.
4Check the statements
- Open Reports → All Reports → Consolidated Statement of Profit or Loss for 2026.
- Open Consolidated Statement of Cash Flows for 2026, and look at the bottom of it.
Check
On the profit or loss, Distribution Costs is 310,000, Administrative Expenses 520,000 and Operating Profit still 1,304,000. On the cash flow, Effect of Exchange Rate Changes on Cash is down to -3,250, a size that fits Company B’s and Company C’s cash being translated, and Cash and Cash Equivalents at End of Period is 1,402,350, the bank balance.
5If something goes wrong
| Effect of Exchange Rate Changes on Cash is still large | A movement isn’t on any line — often a new loan, or an asset bought into an account that isn’t classified. Find the account that moved and put it on its line. |
|---|---|
| Other Operating Expenses is negative | A line has an account that isn’t an expense. Move it off Distribution Costs or Administrative Expenses. |
| The same account cannot be used for multiple classifications within the same standard. | One account is on two CF lines, or on two Equity or P&L lines. Keep it on one of each. |
| [Account] is an equity account, so it cannot be assigned to a P&L classification. | The account was changed to an equity account while this page was open. Reload the page: the account is no longer on the P&L line, and the save goes through. |
Want more detail? See the documentation