
US GAAP Groups · Track 3 · Tutorial 4 of 4
Read the statement of cash flows
Available on ProPremium
The US GAAP cash flow statement explains the year’s change in the group’s cash. Operating cash flow is worked out from net income, with interest left in it as ASC 230 requires; investing and financing flows come from the accounts you classified; and the statement ends at the bank balance.
1Know how the statement is built
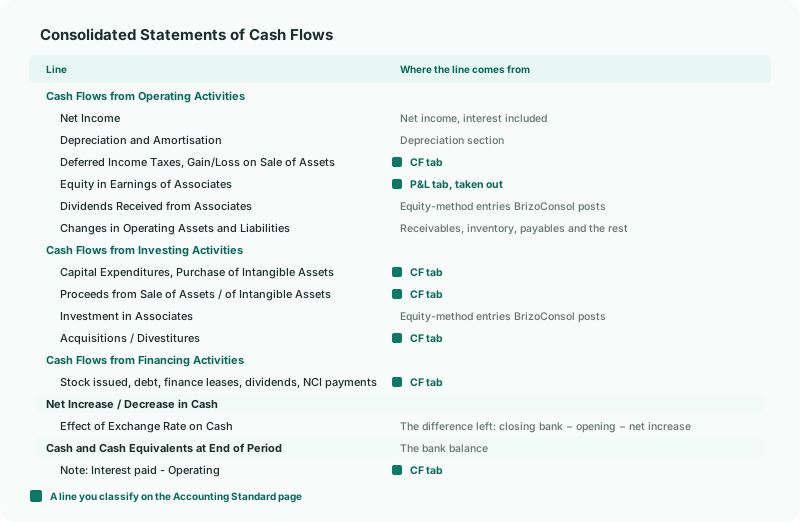
| Operating activities | The indirect method. Net income, plus depreciation and amortisation and deferred income taxes, less the gain on sale of assets and the equity in earnings of associates, plus dividends received from associates, plus the change in receivables, inventory, other current assets, payables, payroll, taxes and other current liabilities. |
|---|---|
| Investing activities | The year’s movement on the accounts classified on each line, and the cash paid for associates. |
| Financing activities | The movement on the accounts classified on each line. |
| Effect of Exchange Rate on Cash | What is left: the bank balance at the end, less the balance at the start, less the net increase from the three sections. |
2Read each section
- Select Your Group, and open Reports → All Reports → Consolidated Statements of Cash Flows for 2026.
| Interest | ASC 230 puts interest paid and received in operating activities. They are in net income, so the statement leaves them there. Note: Interest paid - Operating, under the statement, shows the interest paid from the account classified on Interest Paid. |
|---|---|
| Associates | The group’s share of an associate’s profit is in net income but isn’t cash, so Equity in Earnings of Associates takes it out. Dividends Received from Associates, the cash it actually paid the group, is a return on the investment and stays in operating. Investment in Associates, under investing, is the cash paid for the stake. All three come from the entries BrizoConsol posts — see Account for associates and joint ventures. |
| Stock issues and dividends | An equity account keeps its equity line and can also be given a cash flow line. For a stock issue, put 3000 Share Capital on Proceeds from Issuance of Common Stock as well as on Common Stock. Put the account dividends are recorded in on Dividends Paid. |
| Finance leases | The principal paid on a finance lease is on Principal Payments on Finance Leases, under financing. The interest on it stays in operating activities. |
An account can be on one cash flow line, and on one Equity or P&L line.
3Check the statement ends at the bank
- Open the group’s Balance Sheet at the end of the same period.
Check
Cash and Cash Equivalents at End of Period equals the bank balance — 1,402,350 for Your Group. Effect of Exchange Rate on Cash is small, -3,250, which fits translating Company B’s and Company C’s cash.
The end of period always equals the bank balance, because the effect line takes up whatever the three sections don’t explain. So check the effect line, not the end: a large one means a movement isn’t on any line.
4If something goes wrong
| Effect of Exchange Rate on Cash is large | A cash movement isn’t on any line — often a new loan, an asset bought into an account that isn’t classified, a stock issue or a dividend. Find the account that moved and classify it on the CF tab. |
| Proceeds from Issuance of Common Stock is empty after a stock issue | Share Capital isn’t on the cash flow line. Add it on the CF tab; it keeps its equity line. |
| Equity in Earnings of Associates is empty, but the group has an associate | The share of profit account isn’t on Equity in Earnings of Associates. Classify it on the P&L tab. |
| The same account cannot be used for multiple classifications within the same standard. | The account is on two cash flow lines, or on two Equity or P&L lines. Keep one of each. |
| Dividends from an associate are missing | BrizoConsol finds the associate’s dividends by the account’s name, such as Dividends Paid. Check what the account is called in the associate’s books. |
Want more detail? See the documentation