
IFRS Groups · Track 3 · Tutorial 2 of 4
Follow other comprehensive income into the reserves
Available on ProPremium
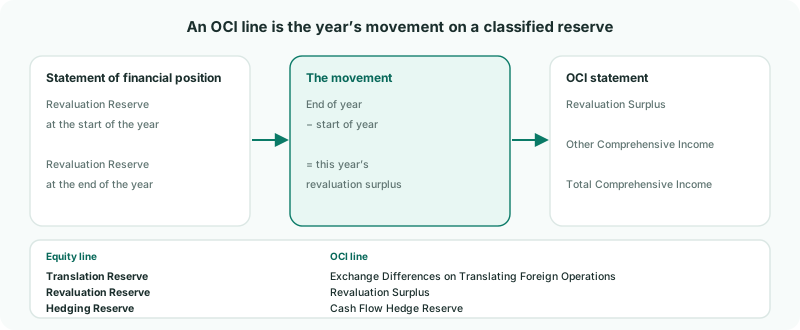
Other comprehensive income is the part of the year’s result that goes straight to a reserve instead of through profit or loss: exchange differences, revaluations, hedges. The IFRS OCI statement reads each line from the movement on the reserve you classified for it.
1Know how the statement is built
| Profit for the Year | The group’s net profit, then split between Owners of the Parent and Non-Controlling Interests, as on the IFRS profit and loss. |
|---|---|
| The OCI lines | Each is the movement in the period on one reserve, or on one of the NCI accounts that hold the NCI’s share of the reserves. |
| Total Comprehensive Income | Profit for the Year plus Other Comprehensive Income. |
| Attributable to Owners of the Parent | Total comprehensive income less the NCI’s part. |
| Attributable to Non-Controlling Interests | The NCI’s share of the profit, plus its share of the CTA, plus its share of the other reserves. |
| OCI line | Reads the movement on |
|---|---|
| Share of OCI of Associates | Share of OCI of Associates |
| Exchange Differences on Translating Foreign Operations | Cumulative Translation Adjustment — 3500 CTA Reserve for Your Group |
| Revaluation Surplus | Revaluation Reserve — 3400 Revaluation Reserve |
| Cash Flow Hedge Reserve | Hedging Reserve |
| FVOCI Reserve | FVOCI Reserve |
| Non-Controlling Interests Share of CTA | The NCI share of CTA account — 3620 NCI Share of CTA for Your Group |
| Non-Controlling Interests Share of Other Reserves | The NCI share of other reserves account chosen in Posting accounts |
2Read the OCI
- Select Your Group, and open Reports → All Reports → Consolidated Statement of Profit or Loss and Other Comprehensive Income for 2026.
| Exchange differences | The owners’ part of the difference from translating Company B and Company C: the movement on 3500 CTA Reserve. The NCI’s 20% of Company B’s part, the movement on 3620 NCI Share of CTA, is on its own line, Non-Controlling Interests Share of CTA. |
|---|---|
| Share of OCI of associates | The group’s share of an associate’s OCI, posted by BrizoConsol — 6,000 for Company G in Account for associates and joint ventures. |
| Revaluation, hedging, FVOCI | The movement on each reserve, through the accounts mapped to the classified group account. A line with no account classified shows nothing. When a foreign subsidiary holds the reserve, the exchange difference from retranslating it isn’t on this line: it is part of the translation reserve, and of Exchange Differences. |
| NCI share of other reserves | The NCI’s share of the movements on those reserves, posted by BrizoConsol to the NCI share of other reserves account. Shows nothing if the group has no such account, or a partly owned company has no reserve movements. |
Under the total, the two attribution lines split it: the NCI receives its share of the profit, the CTA and the other reserves, and the owners receive the rest.
3Trace each line to its reserve
- Open Consolidated Statement of Changes in Equity for 2026.
- Compare each OCI line with the Other Comprehensive Income row of the matching component.
| OCI line | Equals, on the statement of changes in equity |
|---|---|
| Exchange Differences on Translating Foreign Operations | Translation Reserve’s OCI row |
| Revaluation Surplus, Cash Flow Hedge Reserve, FVOCI Reserve, Share of OCI of Associates | The OCI row of the reserve with the same name |
| Non-Controlling Interests Share of CTA and Share of Other Reserves | Non-Controlling Interests’ OCI row, together |
| Other Comprehensive Income | The Total Equity - Other Comprehensive Income row |
Check
Other Comprehensive Income on the OCI statement equals Total Equity - Other Comprehensive Income on the statement of changes in equity, and Non-Controlling Interests’ OCI row equals its share of the CTA plus its share of the other reserves.
Because a line is the reserve’s movement, anything posted to the reserve shows on it. Post only OCI to an OCI reserve; move amounts between reserves and retained earnings through a journal you can recognise.
4If something goes wrong
| An OCI line is empty, but the reserve moved | The reserve isn’t on its equity line. Classify it on the Equity tab of the Accounting Standard page. |
| An OCI line includes something that isn’t OCI | Something other than OCI was posted to the reserve. Find it in Review → Elim. & Journals Report, and post it to the right account. |
| Share of OCI of Associates is empty | Classify the associate OCI reserve on Share of OCI of Associates, as in Account for associates and joint ventures. |
| Non-Controlling Interests Share of Other Reserves is empty, but a partly owned company’s reserves moved | The group has no NCI share of other reserves account. Choose or create one in Posting accounts, on the Ownership page. |
Want more detail? See the documentation