
F&B Groups · Track 2 · Tutorial 1 of 2
Eliminate restaurant loans and reverse their impairment
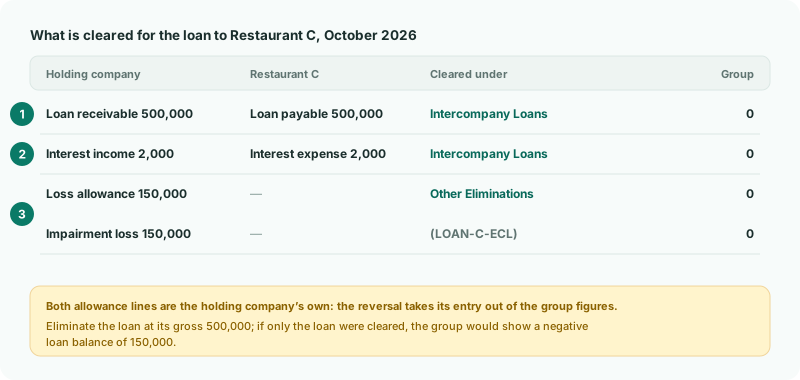
When a restaurant struggles, the company that lent it money books a loss allowance against the loan. The group has no such loan, so the allowance comes out with it, or the group shows an impairment of money it owes itself.
1Know what to eliminate
The holding company lent Restaurant C 500,000 for its fit-out, at interest of 2,000 a month. Restaurant C is struggling, so in October 2026 the holding company books a loss allowance of 150,000 against the loan under IFRS 9, with an impairment loss of 150,000 in its profit and loss.
| The loan | The holding company’s receivable against Restaurant C’s payable: 500,000. |
|---|---|
| The interest | The holding company’s interest income against Restaurant C’s interest expense: 2,000 a month. |
| The impairment | The holding company’s loss allowance of 150,000 and its impairment loss of 150,000. |
For the group the loan doesn’t exist, so it can’t be impaired: the allowance and the impairment loss are reversed as well as the loan and the interest. Restaurant C’s difficulties are still there for the group — in its own assets, which are tested for impairment under IAS 36.
2Eliminate the loan and the interest
Clear the loan and the interest under Intercompany Loans, with a rule or an entry, as in Eliminate loans and interest. Under Intercompany Loans an entry’s lines can use Current Asset, Non Current Asset, Current Liability, Non Current Liability, Interest Income and Interest Expense accounts.
Eliminate the loan at its gross amount, 500,000, on both sides. The allowance is on its own account and is reversed in the next step.
3Reverse the impairment
Intercompany Loans doesn’t accept the impairment loss, an expense account. Other Eliminations accepts any account, so the reversal goes there.
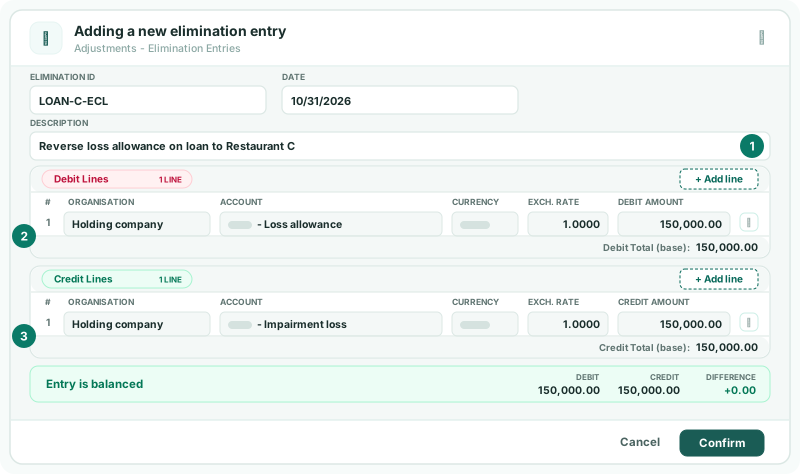
- Open Intercompany → Other Eliminations, choose Oct-2026, and click Add a new Elimination Entry.
- Enter an Elimination ID, such as LOAN-C-ECL, and a Description: “Reverse loss allowance on loan to Restaurant C”.
- Under Debit Lines, choose the holding company and its loss allowance account, 150,000.00.
- Under Credit Lines, choose the holding company and its impairment loss account, 150,000.00.
- Click Confirm.
Both lines are the holding company’s: the reversal takes its own entry out of the group figures. The entry stays in later months as it was posted, so when the allowance changes, enter only the change.
Check
On the group’s Balance Sheet for Oct-2026 with Show Entities on, the loan receivable, the loss allowance and Restaurant C’s loan payable are zero in the group column. On the Profit & Loss, the impairment loss and the interest on the loan are zero in the group column.
4If something goes wrong
| … cannot be used in this elimination type. | The impairment loss was entered under Intercompany Loans. Enter it under Other Eliminations. |
|---|---|
| The group shows a negative loan balance of 150,000 | The loan was eliminated at its gross amount but the allowance wasn’t reversed. Add the entry in step 3. |
| The impairment loss is still in the group’s profit | The reversal is in a different month from the allowance. Enter it in the month the holding company booked the allowance. |
Want more detail? See the documentation