
US GAAP Groups · Track 2 · Tutorial 1 of 3
Measure NCI at fair value in a business combination
Available on ProPremium
When the group buys control of a company but not all of it, ASC 805 measures the noncontrolling interest at its fair value on the acquisition date. That sets the NCI and the goodwill on the day of the purchase.
1Know how the NCI is measured
In September 2026, Your Group buys 80% of Company F for 960,000. The purchase price allocation values Company F’s identifiable net assets at 1,000,000, and the 20% the group didn’t buy at 230,000.
| The NCI | Starts at its own fair value: 230,000. |
|---|---|
| Goodwill | The investment cost plus the NCI less the net assets at fair value: 960,000 + 230,000 − 1,000,000 = 190,000. It includes the NCI’s share of goodwill. |
US GAAP has no choice here. Measuring the NCI at its share of net assets, which IFRS allows, would give an NCI of 200,000 and goodwill of 160,000; under US GAAP, use fair value for every acquisition.
2Get the NCI’s fair value
The NCI’s fair value comes from the purchase price allocation, alongside the fair value of the net assets. It isn’t simply 20% of what the group paid for 80%: the price for control usually includes a premium the minority shares don’t carry. Here, 20% of the price would be 240,000; the valuation puts the NCI at 230,000.
3Record the acquisition
- Open Ownership & Equity → Ownership, and click Company F in Group structure.
- Under Share purchases and sales, click + Record, then Bought shares.
- Choose Your Group as Parent entity, Sep 2026 as the Month, 80 as the % transacted, and Subsidiary.
- Enter the Investment cost (960,000) and Net assets at date (fair value) (1,000,000), in the group currency.
- Under NCI measurement, choose Fair value of NCI (full goodwill), and enter the NCI fair value (230,000).
- Click Add Record.
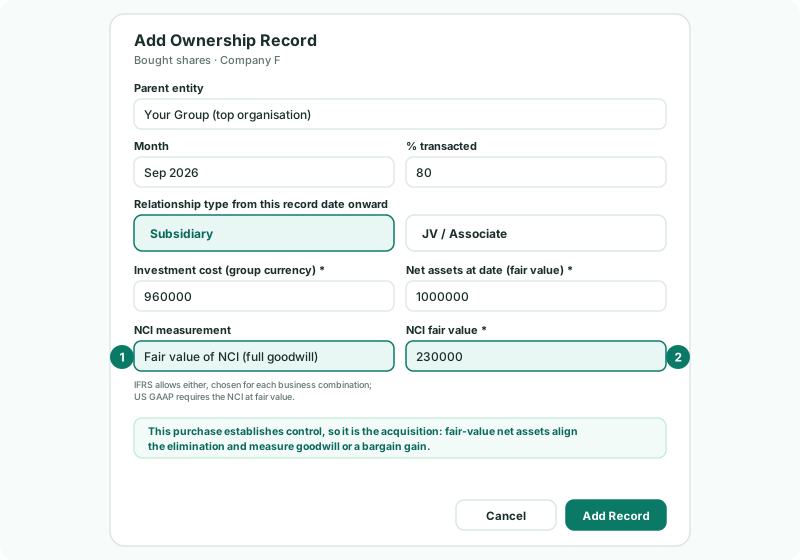
NCI measurement appears only on the record that gives the group control. It starts on Share of net assets (partial goodwill), so change it to fair value on every acquisition.
Then open Totals and accounts for this company and choose the investment and goodwill accounts, as in Buy a new subsidiary.
4Check the goodwill and NCI
- Open Company F’s Totals and accounts for this company.
- Open Reports → All Reports → Consolidated Balance Sheets for 2026.
Check
Acquisition goodwill shows 190,000. On the US GAAP balance sheets, the goodwill account carries the 190,000 within non-current assets, and Non-Controlling Interests includes Company F’s 230,000 plus its share of Company F’s net income since September.
After the purchase, the NCI takes its 20% of Company F’s net income and other comprehensive income. On the US GAAP profit and loss, it is the Non-Controlling Interests line under Net Income Attributable to.
5If something goes wrong
| Goodwill is 160,000 and the NCI 200,000 | The record was saved with Share of net assets (partial goodwill). Edit it, choose Fair value of NCI (full goodwill), enter the fair value, and click Save Changes. |
|---|---|
| NCI fair value is required when NCI is measured at fair value. | Enter the NCI’s fair value from the purchase price allocation. |
| Net assets at date (fair value) is required for the acquisition that establishes control. | Enter the net assets at fair value from the purchase price allocation. |
| NCI measurement isn’t in the dialog | The record doesn’t give the group control — for example, it is a later purchase in a company the group already controls, or it is set to JV / Associate. |
| Bargain purchase gain appears instead of goodwill | The investment cost plus the NCI is less than the net assets at fair value. Check the three figures against the purchase price allocation. |
| The goodwill is wrong after the valuation is finalised | Edit the ownership record with the final figures, and click Save Changes. |
Want more detail? See the documentation